

The Yuan trade
I am not entirely sure what is happening in a macro-economic scale, Since I mainly live under a rock.
But I had read on twitter that there is something up with Chinese stocks or whatever, and the whole BRICS fiasco.
Not entirely sure whatever that is about, and I definitely know that my 10 whole braincells cannot comprehend it. But, my gambling nature pushed me to just take a glance at the charts of IV and RV spreads.
I found an ETF that gives exposure to the Chinese yuan, called the WisdomTree Chinese Yuan Strategy Fund(CYB).
Now, let’s look at the typical volatility mispricing element:
Big events + Retail Degenerates gambling and speculating = Vol mispricing.
Both of which are present right now.
I checked data on various timeframes for the CYB Implied and Realised Volatility data and I found something hella interesting in the 60 day window:
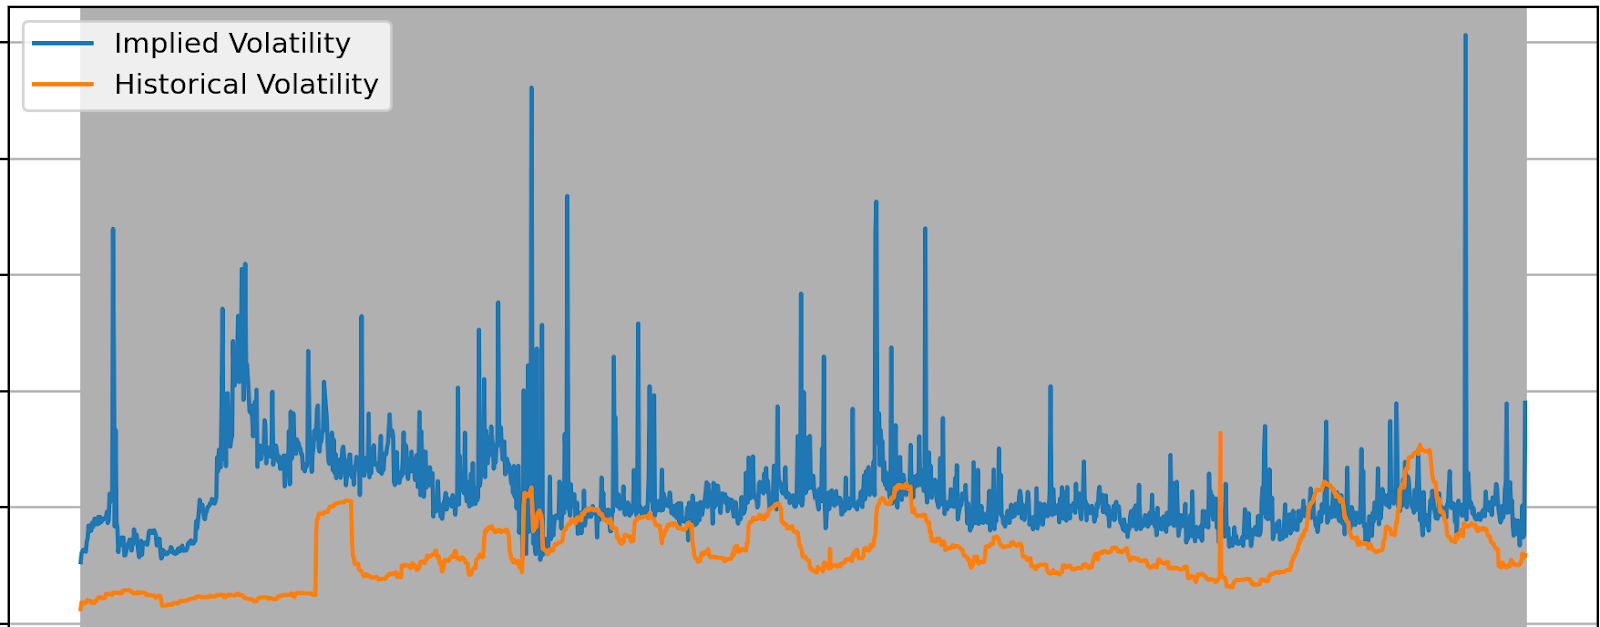
From the get-go we can see that degenerates gamble so much that Implied Volatility is almost always higher than Realised Volatility.
But, the major part of the thesis is:
The options market is implying a high volatility… which was never realised before.
Sooo many people high on caffeine and adderall drove the speculation soo high that the options market has implied something about 20-30 times in the past, and it never happened, and yet, it implies the same volatility again.
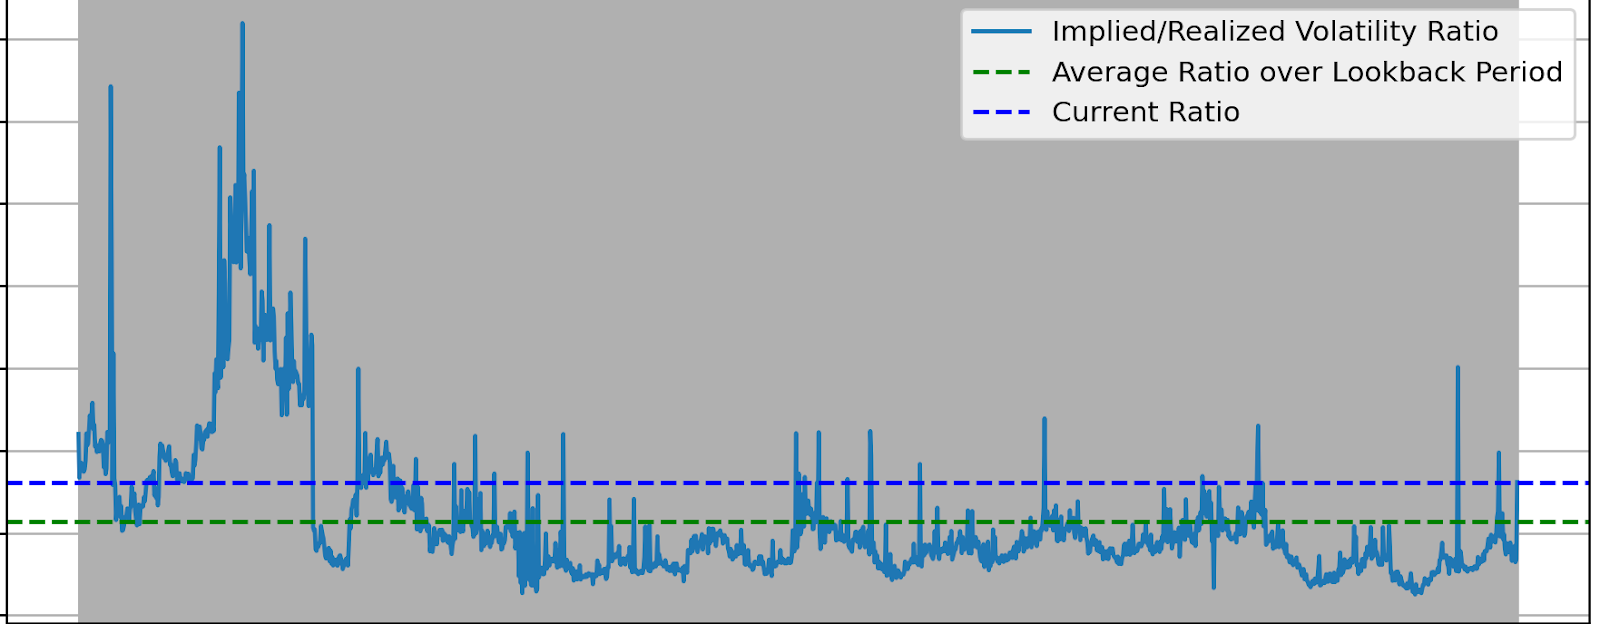
I feel that this kind of graph is something every volatility arbitrageur would want to see.
To all the high speculators, Thank you
The trade:
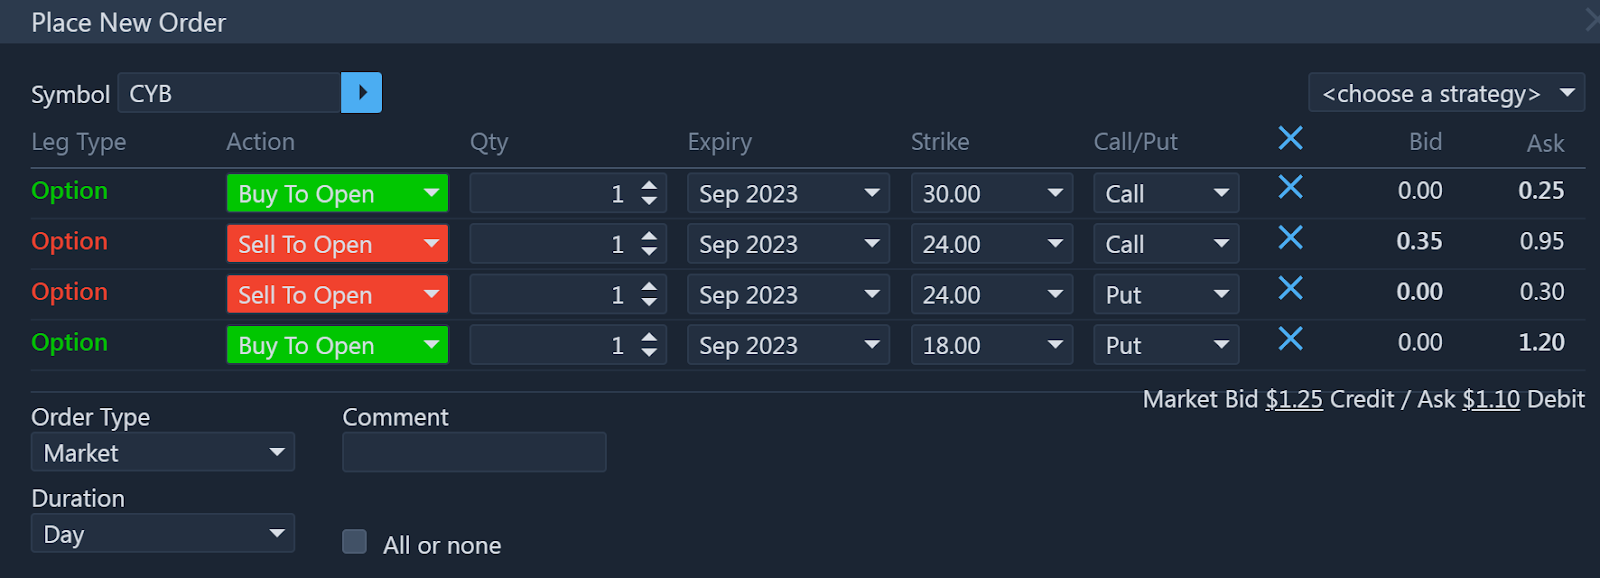
The OTM call and put are used as a hedge to make my risk defined, since all trades have risks, let alone trades carried out by me.
An alternate trade:
For those of you that don’t have it in your risk appetite, to hold longer dated option, I saw that this situation is even seen in the 10 day Implied and Realised volatility spread. Sadly, you lot will have to wait a bit from the date of this writing to have a 10-day holding period option in your horizon.