


While the rest of the market chases high valuation names with strong ‘growth‘ potentials, we are much more intrigued by the hidden gems trading at a depressed valuation due to the market overlooking value in the balance sheet, just because the value in the income statement has diminished.
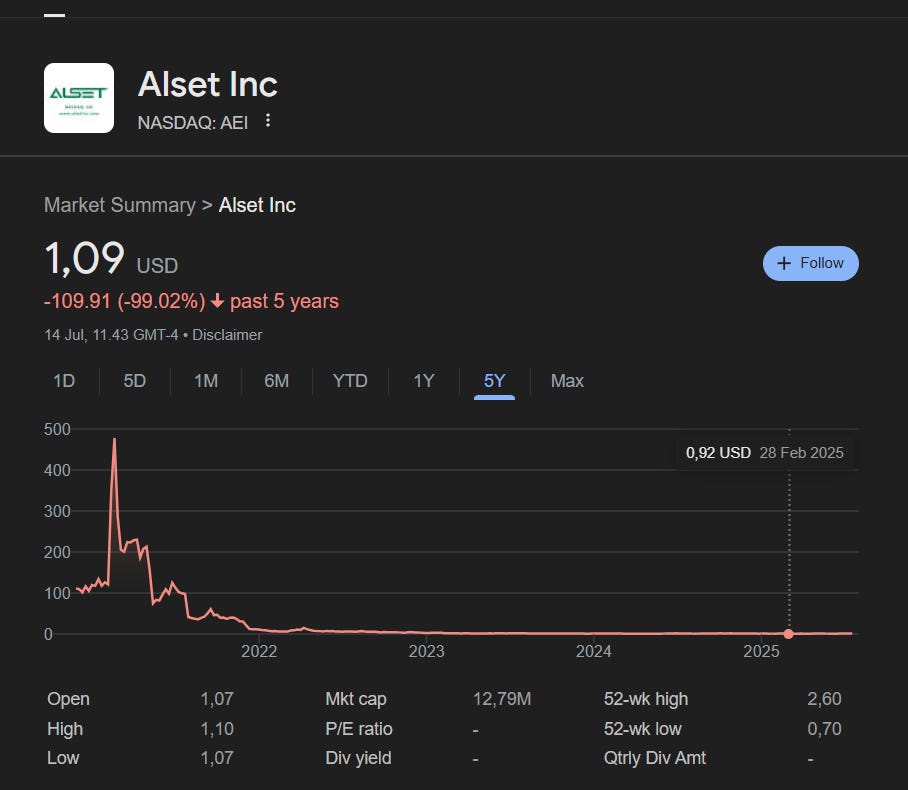
Today we present to you AEI: Alset Inc. At first glance, the share price performance has been abysmal
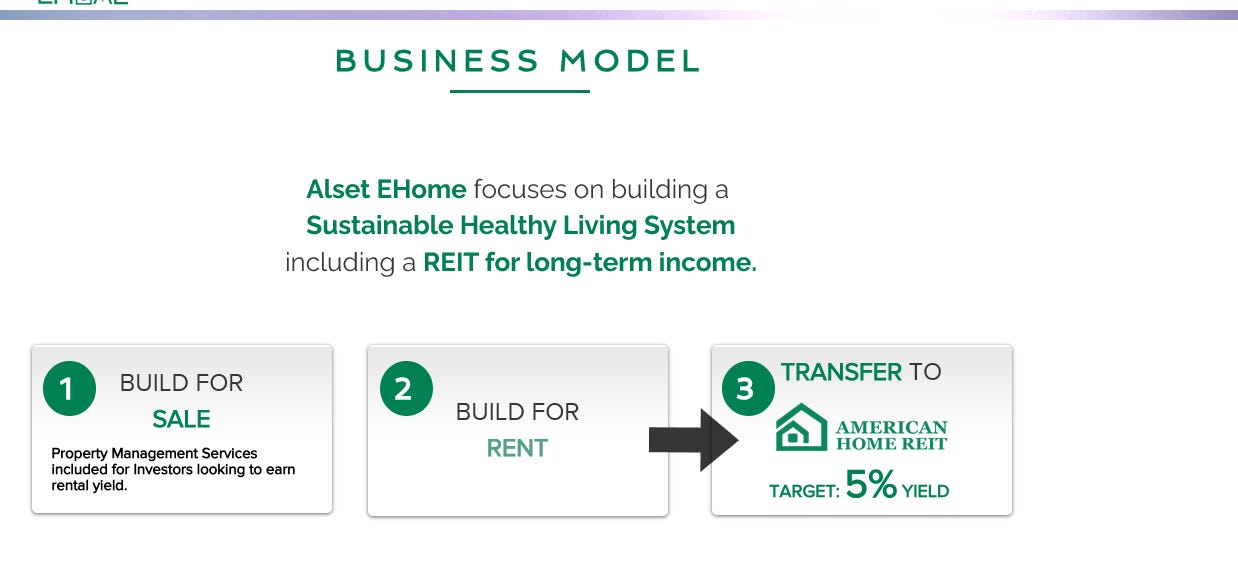
AEI’s main business is real estate:
Now, a huge reason for the disappointing share price performance is due to AEI’s pivot into this real estate sector. Before AEI’s full pivot into its current business iteration, AEI served as a ‘solar home maker/installer‘ for none other than Tesla
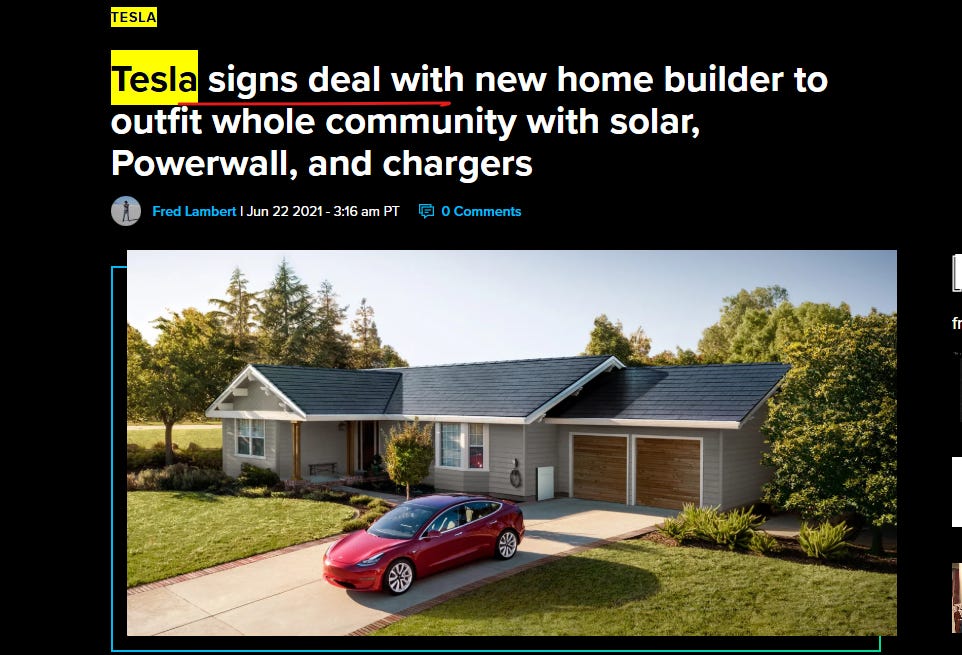
This undoubtedly was one of the key reasons for the sky high prices of AEI back in 2021. However, for whatever reason, the deal either did not materialize or AEI pivoted away from this, which is one of the primary reasons for the share price drop, and we think shares haven’t recovered due to the illiquidity, and complicated structure in the company. However, in this nanocap valuation, we think AEI is a buy for the following very simple reasons:
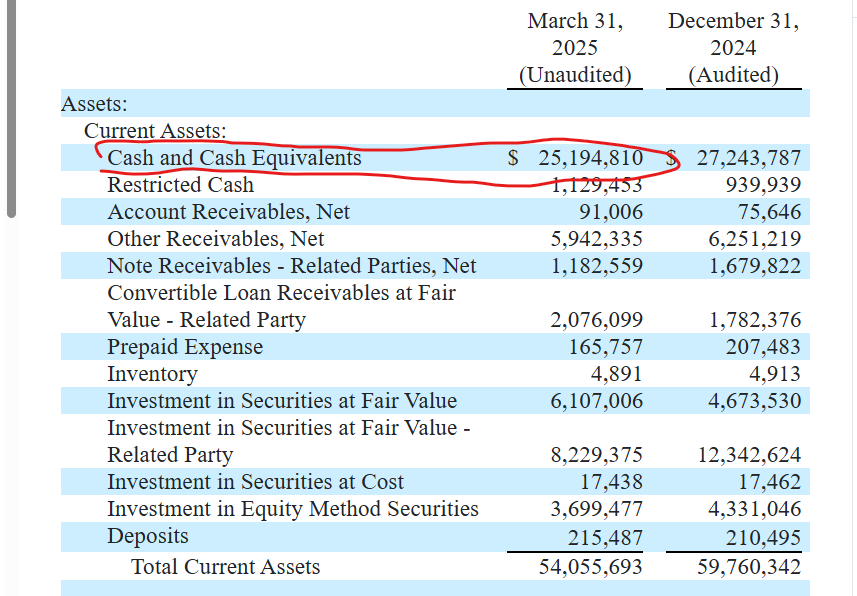
AEI, with a market cap of 13 million, has about 20 million dollars in cash. Dissatisfied with where they are trading, the company has announced a 1 million dollar buyback using this cash.
At the most recent Q1 2025 financials, AEI had about 25 million dollars worth of cash:
And a total liability balance of 5 million dollars:
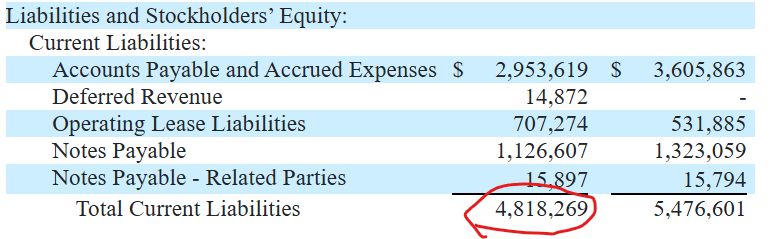
This gives a total net cash balance of about 20 million dollars, a hugely comfortable position for a company with a market cap of 13 million dollars.
However, we all hate cash squatting companies that don’t allocate any of that extra cash for the benefit of their shareholders, which might be one of the reasons the stock is trading so low! The company has not taken any steps to turn the balance sheet value into shareholder value. This was until we saw the following announcement by the company:
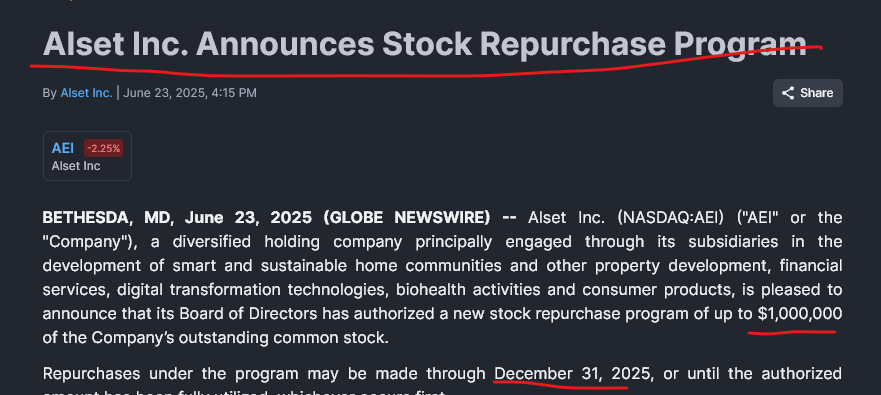
This buyback plan, if executed, would retire about 8% of the company’s shares by December 2025. Looks like the company finally got the memo! This is a company actively turning its potential balance sheet value into shareholder value! This is a huge part of why we are long.
Along with this cash, AEI owns about 132 single family residential properties as well, which while we don’t exactly see as ‘liquid’ investments, it still counts for something.
In the extremely unlikely scenario where the company enters a state where it needs to squabble for cash, it still owns about 132 Single Family properties:
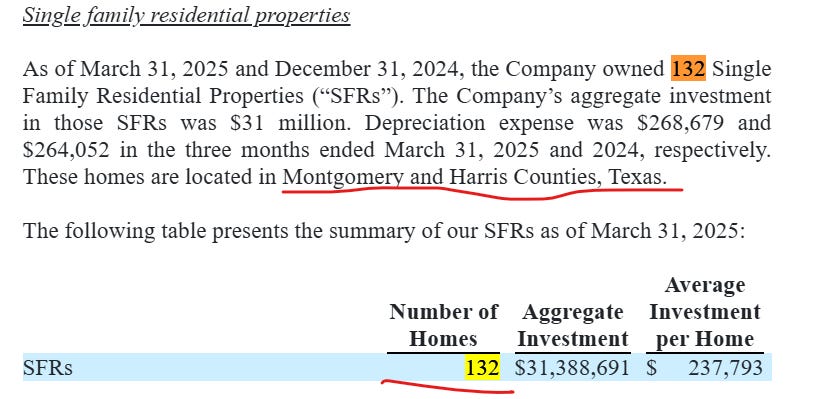
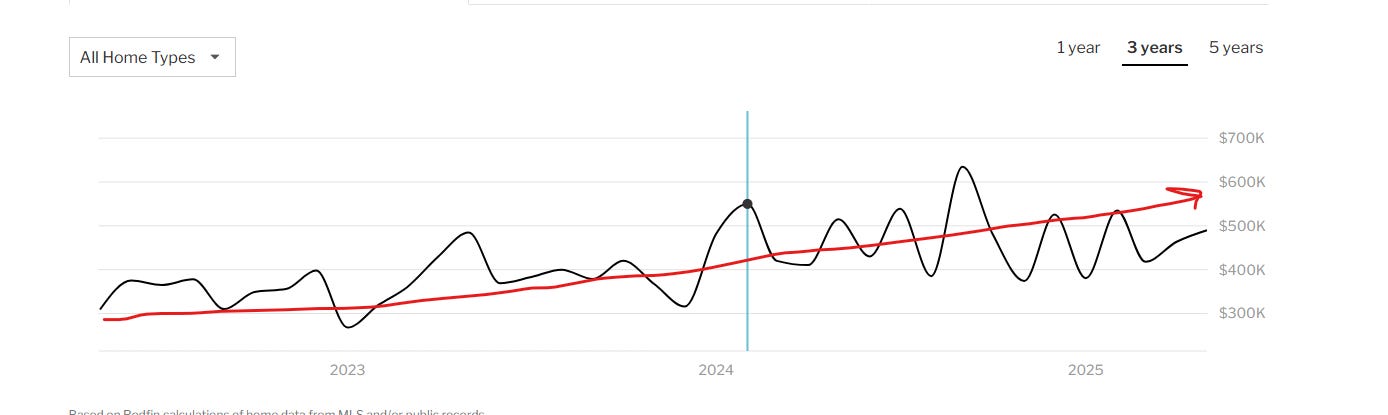
Note that the place these homes are located is in Montgomery and Harris Counties, with the median house prices in this region increasing over the past 3 years:
In fact, in late 2024, AEI, through its subsidiary, sold some of its residential properties for 4 million dollars:
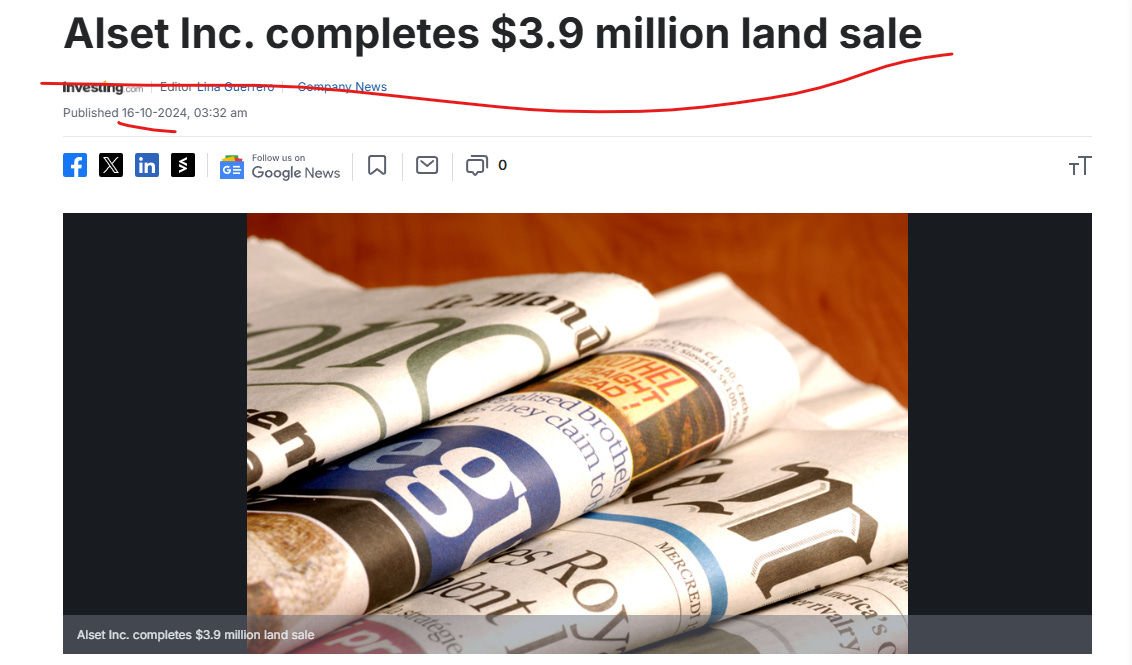
While this may not sound a lot, it signals to us that in addition to the copious amounts of cash the company has, some value exists in the residential homes it owns, and the company is committed to return some of this value to shareholders via buybacks!
AEI’s CEO bought a few shares earlier this year, which we love to see, since if management doesn’t believe in their own company, why would investors do so ?
We think insider buys from the CEO in a deep value nanocap shitco is one of the best indicators of outperformance, all things considered.
For everyone who checks insider transactions using Finviz, the following insider buy from just 2 weeks ago is not reported:
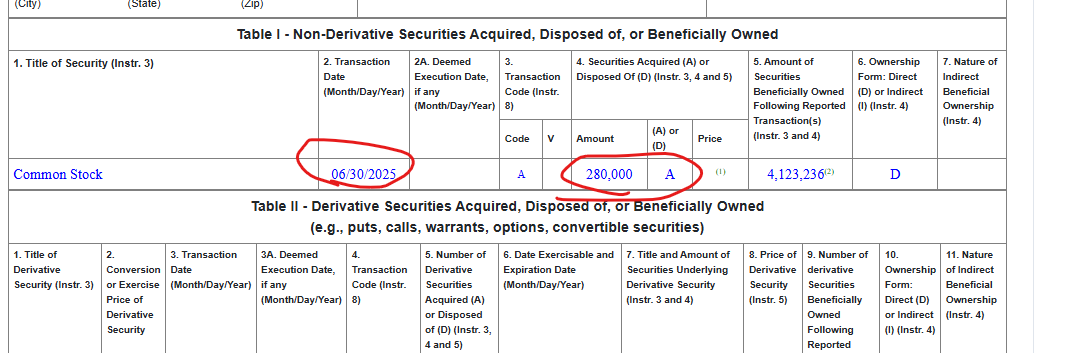
Moreover, Finviz actually shows these two huge insider sale bars by the CEO:
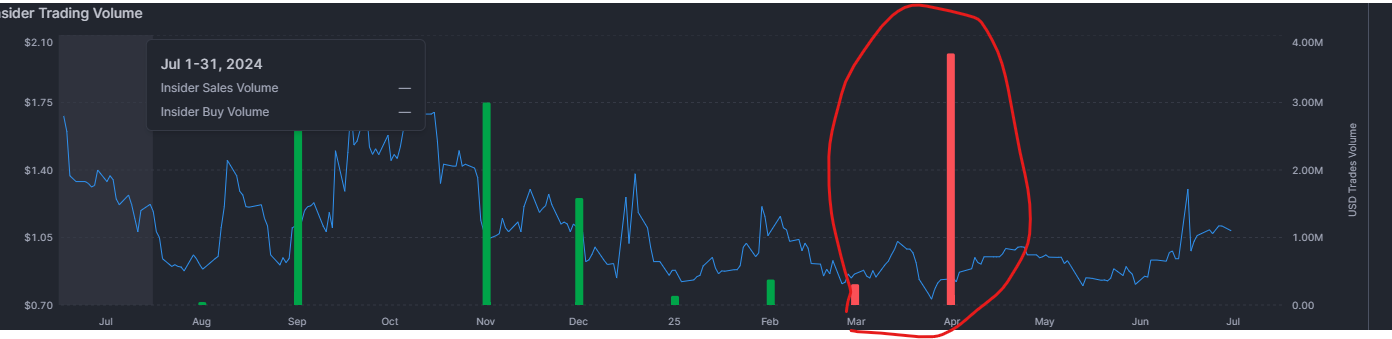
When in reality, these insider sales actually pertain to the CEO selling his shares in another public company with ticker IBO:
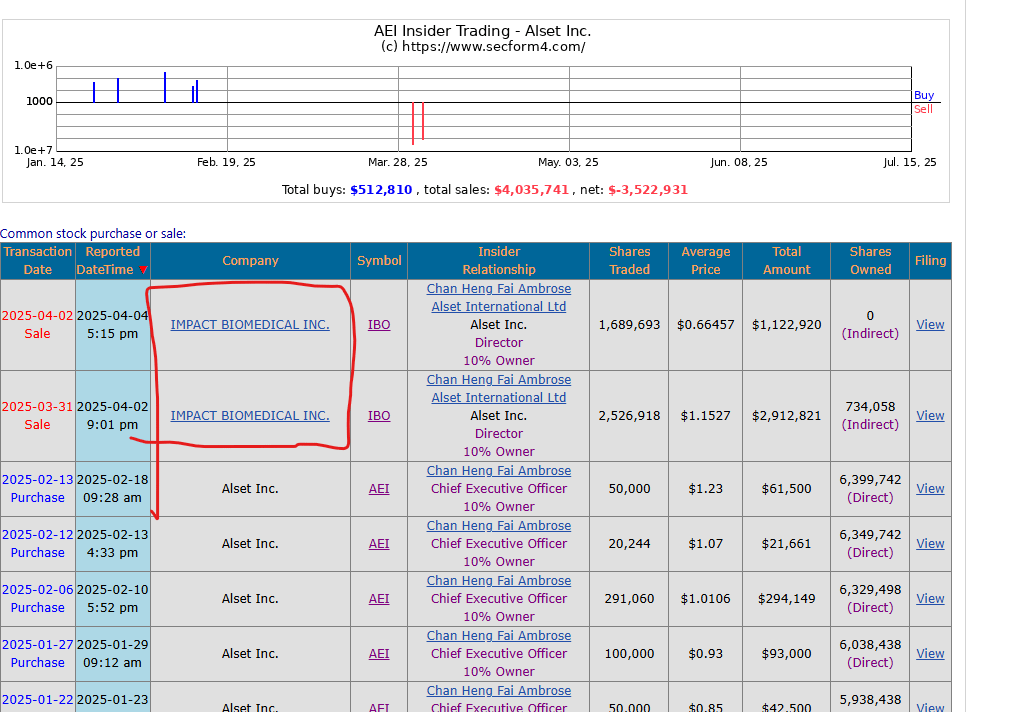
In addition to the insider buys reported on February 2025 in the screenshot above, insider sale trackers that I, and presumably other retail deep value investors follow don’t seem to reflect this huge insider buy made in April of 2025 either:
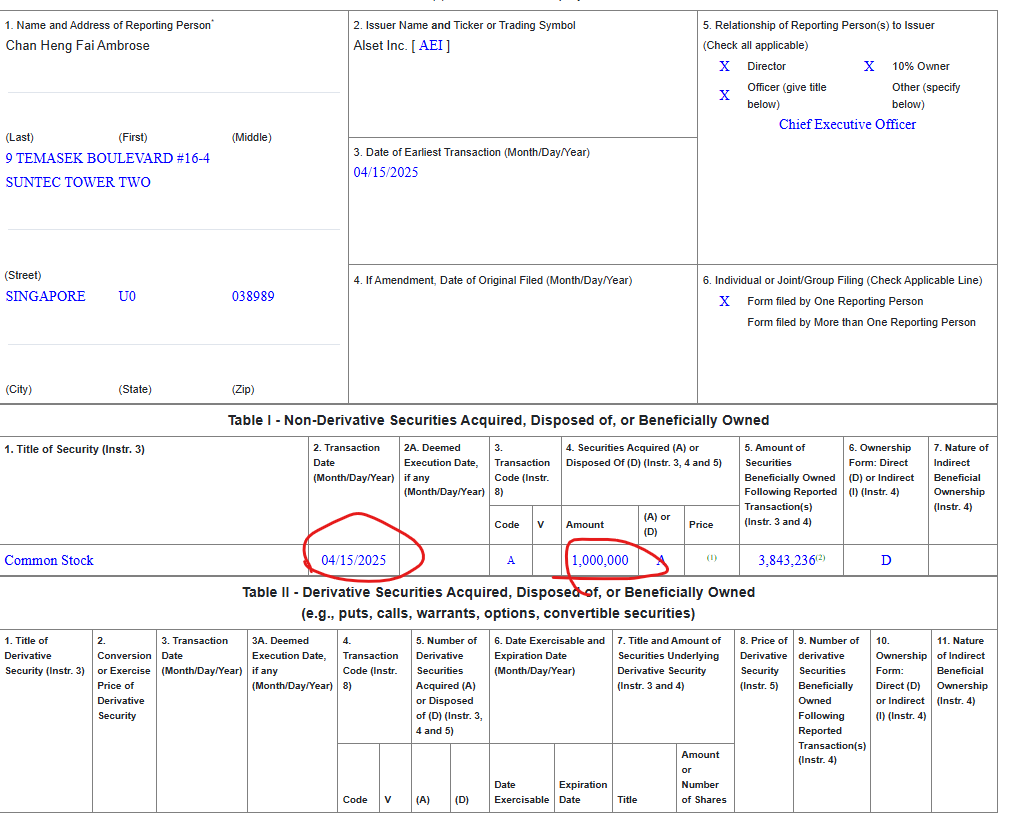
The company is so small and obscure and under-followed, that even automatic insider trading trackers have given up on it! We think the consistent buys from the CEO, in addition to the announced 1 million dollar buyback to drive value creation is all the signs that we need that value will be returned to shareholders, and that this deep value shitco could be a pretty good investment.
Conclusion
At the end of the day, ‘sophisticated‘ investors would shun the stock due to an unreliable income source and due to its narrational pivot away from Tesla. However, there is a tremendous amount of value to be found in the balance sheet, and we have initiated a position now knowing that management is committed to return this to value to shareholders. Sure. It is a nanocap shitco. However, that is what deep value investing is about, and we think that this name has more value to offer than the market perceives.
By reading any of our posts, you agree to do your own due diligence before making any investment decisions. You agree that the authors of this publication are in no way responsible for your investment decisions, and are not liable for any of your possible investment losses, and you also agree to acknowledge that we are do not guarantee any accuracy in our research. You agree to also not proceed with any legal action against us.
The authors of this publication do not give any buy or sell recommendations and do not ensure any correctness to our claims or findings. Under no circumstances would you hold the authors liable for any investment losses. One should assume that any sentence or statement in our posts can be inaccurate and factually incorrect and should not influence anyone’s investing.
Sincerely,
Ragnarok Research

Where do you get a market cap of $13 million? It's more like $50 million right?
The company has been destroying value via a variety of unsuccessful initiatives, and have raised many times. Looks more like a value trap to me.