

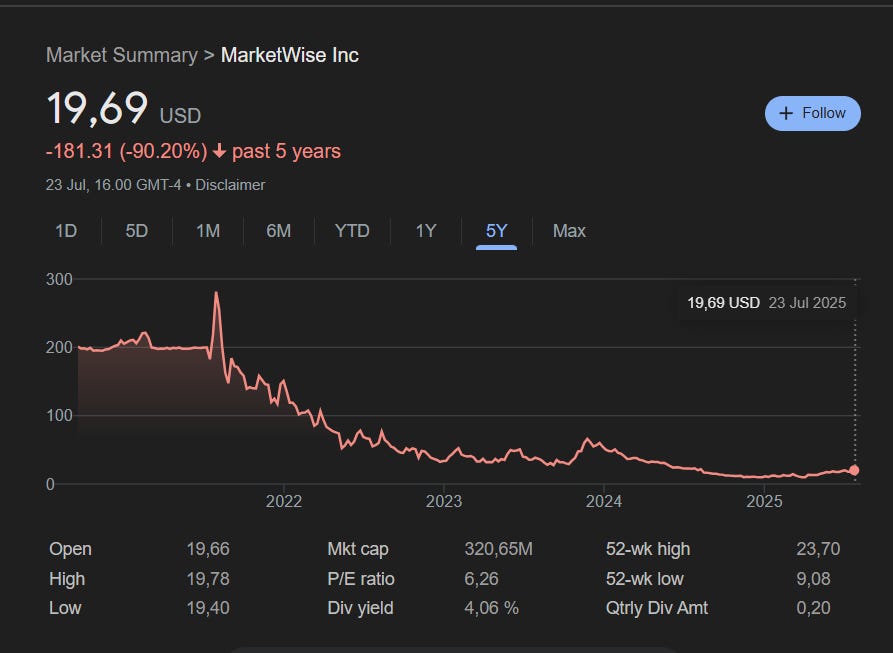
While we typically refrain from buying stocks up a 100% from local lows, we are making an exception with MKTW, since all we see here is a polarising stock valued at an absurdly cheap price due to risks that we think the market is over-exaggerating. This company has gone from priced to perfection, to being priced as if it won’t deliver anything!
We present to you, $MKTW:
MarketWise is an owner of a few companies that publish in-depth research and due diligence primarily for retail investors. Here are the companies it owns:
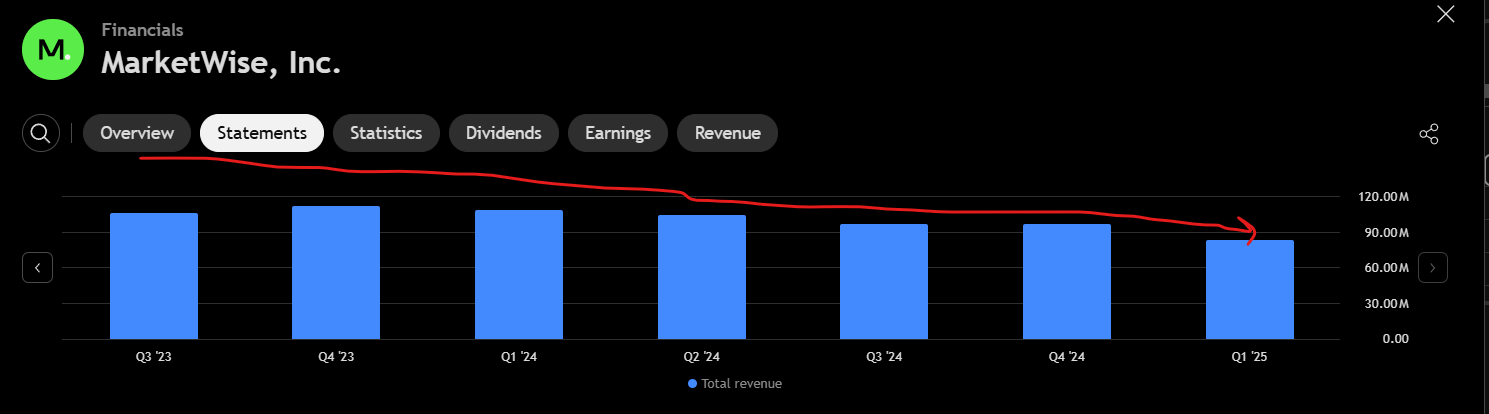
Even though we are bullish on the stock, we empathise with the market for punishing the name this long. For instance, revenue growth has been negative for the past few quarters:
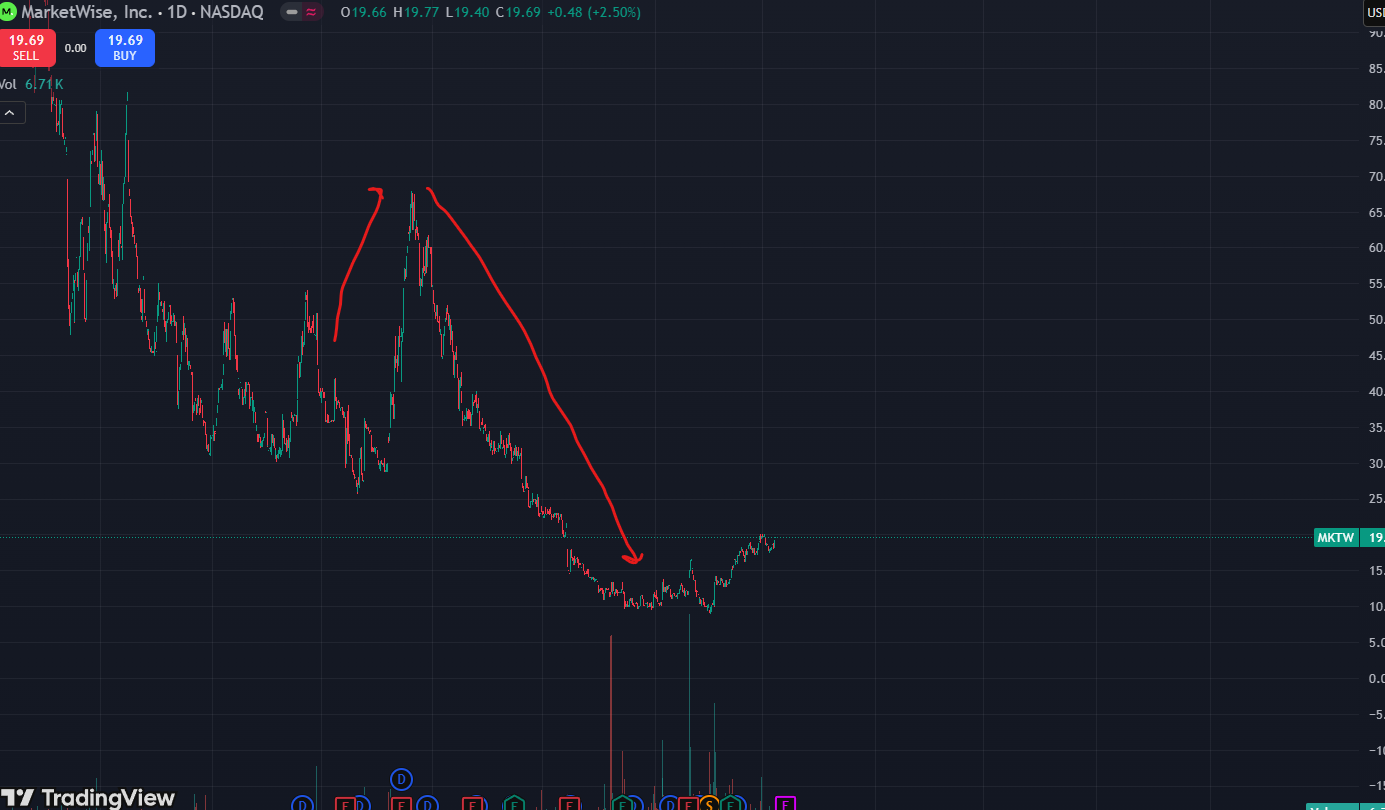
However, while the revenue growth has been extremely abysmal, we think that the market has punished the stock too hard, and continues to not appreciate its recent progress at a turnaround and growth. For context, MKTW did 83 million dollars in revenue this quarter. By annualising this, you get a Price-To-Sales ratio of just 0.96x, and a PE of about 4.9x
Nevertheless, we aren’t ones to buy a stock just because it is cheap. Here is why we see tremendous turnaround potential in MKTW’s share price:
We think the worst is behind us. Net billings are up in recent quarter, and search volume for MKTW companies have been exploding lately. The market thinks something terrible has happened to revenues; but we think MKTW’s core business is resilient
One of the main reasons MKTW revenue and KPIs have been suffering is due to them shutting down a relatively big part of their business called ‘Legacy Research’. This gradual wind-down kicked off in mid 2024, and the stock has reacted rather badly to this:
This wind-down of Legacy Research resulted in a rather ugly decrease in Billings in 2024, which puts a lot of the share price action in 2024 in context:
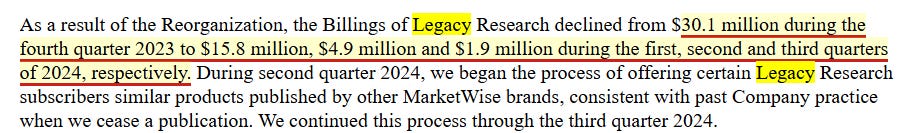
For clarification, total 2024 billings was 240 million dollars
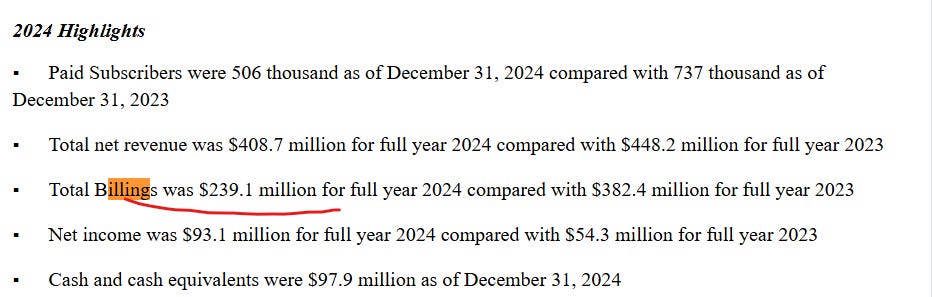
Now while it is true that it did hurt business a little, we think the market taking the stock from about 60 dollars to about 20 dollars is a little bit of an over-reaction, as the market was trying to value MKTW as a company which was losing revenue due to Legacy Research.
However, the most recent Q1 2025 Earnings showed a few things:
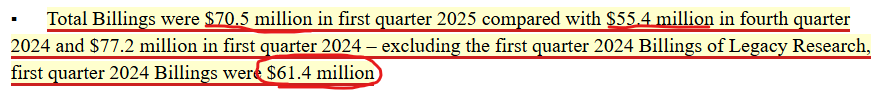
Total billings are up both Quarter-over-Quarter and Year-over-Year(by netting out the impact of Legacy Research). Therefore, we think that MarketWise deserves a re-rating in multiple, as it continues to show that the core business is solid, even without Legacy Research.
Moreover, what investors think is an organic decline in revenue and subscriber counts, seems to us as just an effect of the winding-down of Legacy Research, with the core business still going strong. For example:
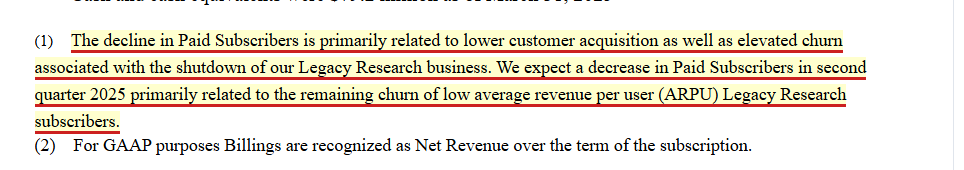
While investors might be spooked by reading that little passage, here is our takeaway: The only users that are leaving, are the low quality, low ARPU ones.
This is also evident in the fact that quarter-over-quarter ARPU has gone UP while subscriber numbers have gone down. This signals to us that the current customer churn is that of the low-quality Legacy Research users:
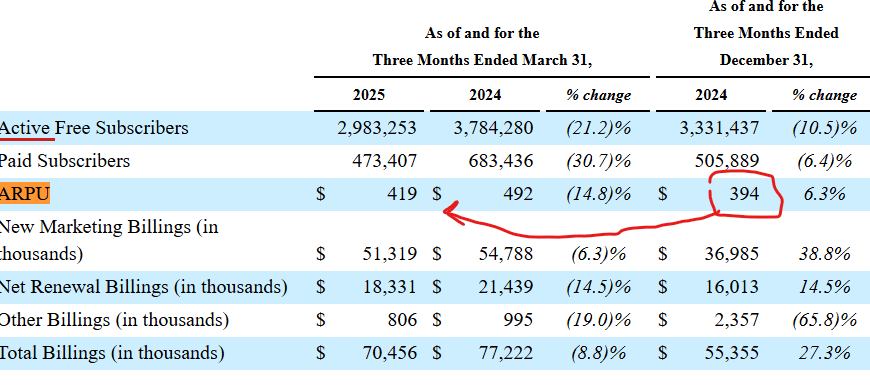
Sure. Some subscribers are leaving, and this might be a negative for a business. But to punish it by rerating it to a 0.96x price-to-sales, and a 4.9x price-to-earnings is just absurd to us, and we think this is a product of the market over-estimating core-business churn and confusing it with low-quality Legacy Research users. Essentially, the company went from being priced to perfection, to being priced to achieve nothing!
Now that the winding down of Legacy Research is mostly completed, we think that MKTW deserves a fresh start by the market as a 4.9x PE company with a healthy balance sheet with potential to grow. The market punished the company by taking it to 60$ a share to about 20$ because of the loss of Legacy Research, but we think that this loss is more than priced in, and the market is overestimating the value of Legacy Research that MKTW lost. Now, it is undervalued with lots of potential to grow. In order to put into context how much potential it has, we analysed web traffic data and deduced that the 2 biggest companies MKTW owns are Stansberry and Brownstone Research. Here is how the data looks for the main companies MKTW owns:
Stansberry Research:
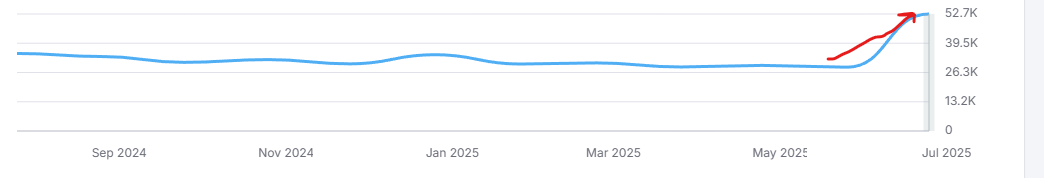
A recent jump in organic traffic to Stansberry research
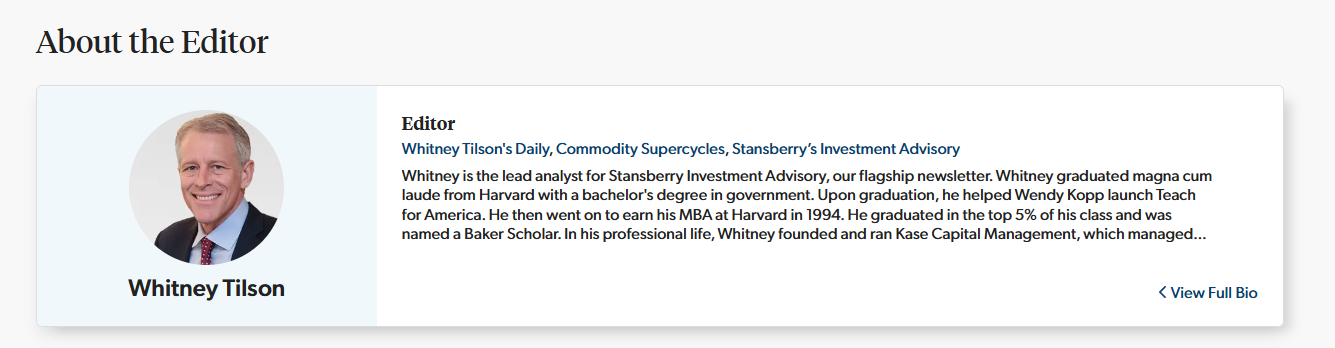
We think a large part of this is due to former NYC mayor candidate and investor Whitney Tilson being an editor at Stansberry:
Moreover, Google trends data shows heightened search activity in Q2 2025:
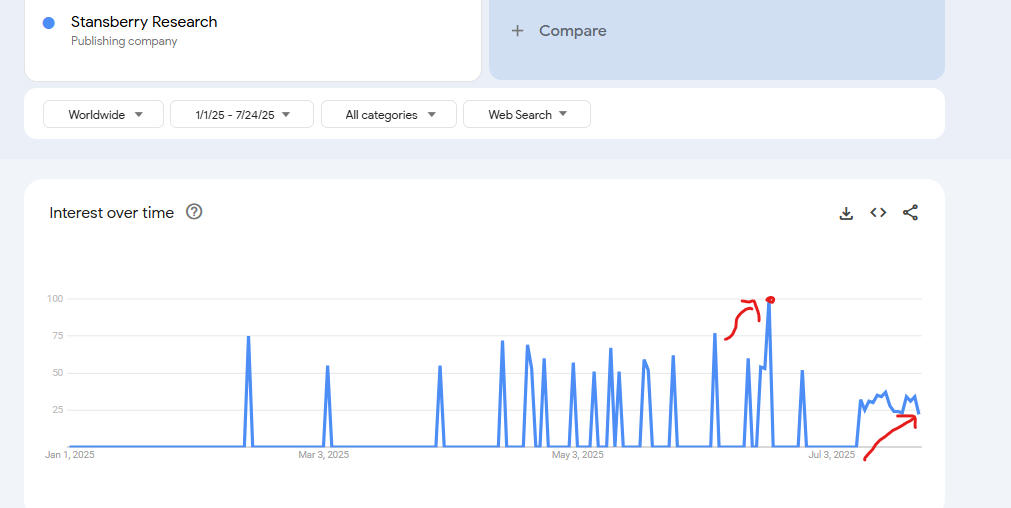
As can be seen above, the higher relative interest points on the graph fall on dates within the Q2-Q3 2025 range. What we find further encouraging is the following:
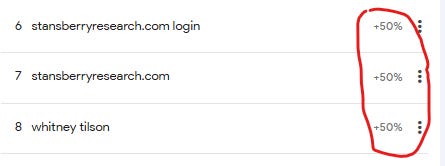
50% Increases form the previous time period in relative search volumes for the login pages of Stansberry and the website itself!
Brownstone Research:
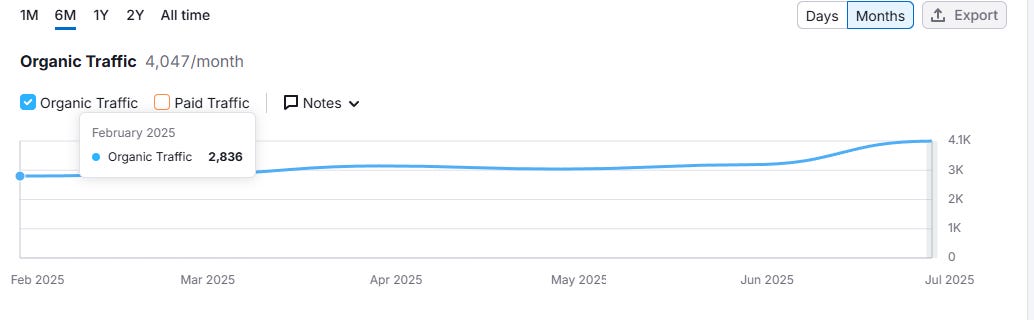
Organic Search traffic has risen about 100% since Feb 2025, with Google trends data showing something similarly encouraging:
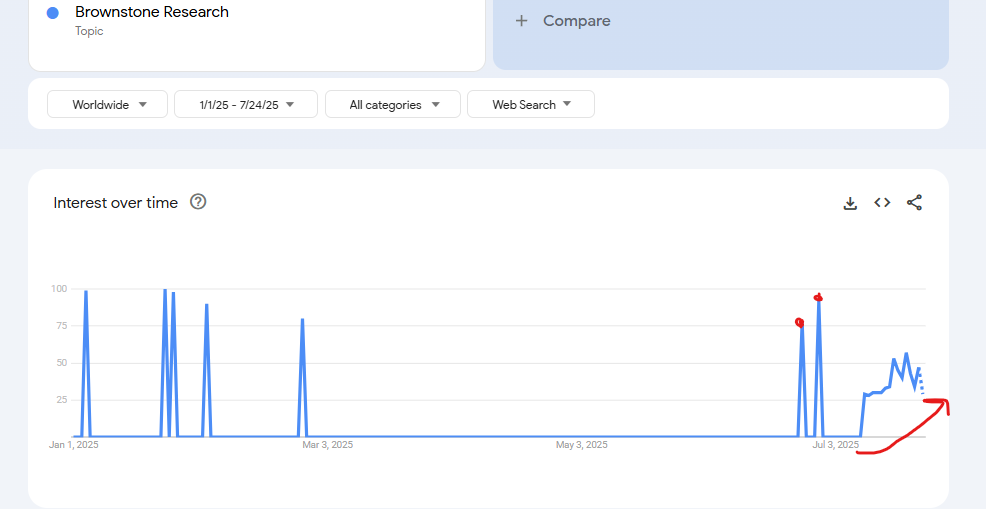
As can be seen, high search volume relative to that seen in January 2025 has increased in frequency in the Q2-Q3 2025 range, and we think this growth is stable. The most encouraging statistic is what we display below:
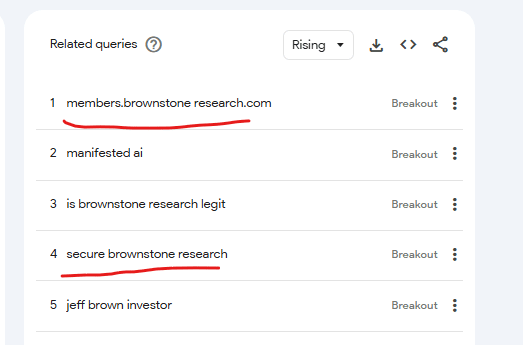
Search volumes for the members url has been on a tear, but also the secure site of Brownstone. For context, secure.brownstone.research is the checkout site where users go to pay for their subscriptions!
Management has committed to improving shareholder returns by authorising a 50 million dollar buyback, and has proved that they have shareholder’s best interests in the past. This should help re-rate MKTW from a cheap 4.9x PE stock to a more accurate valuation
A casual look at the balance sheet reveals that net effective cash balance is around 37 million dollars:
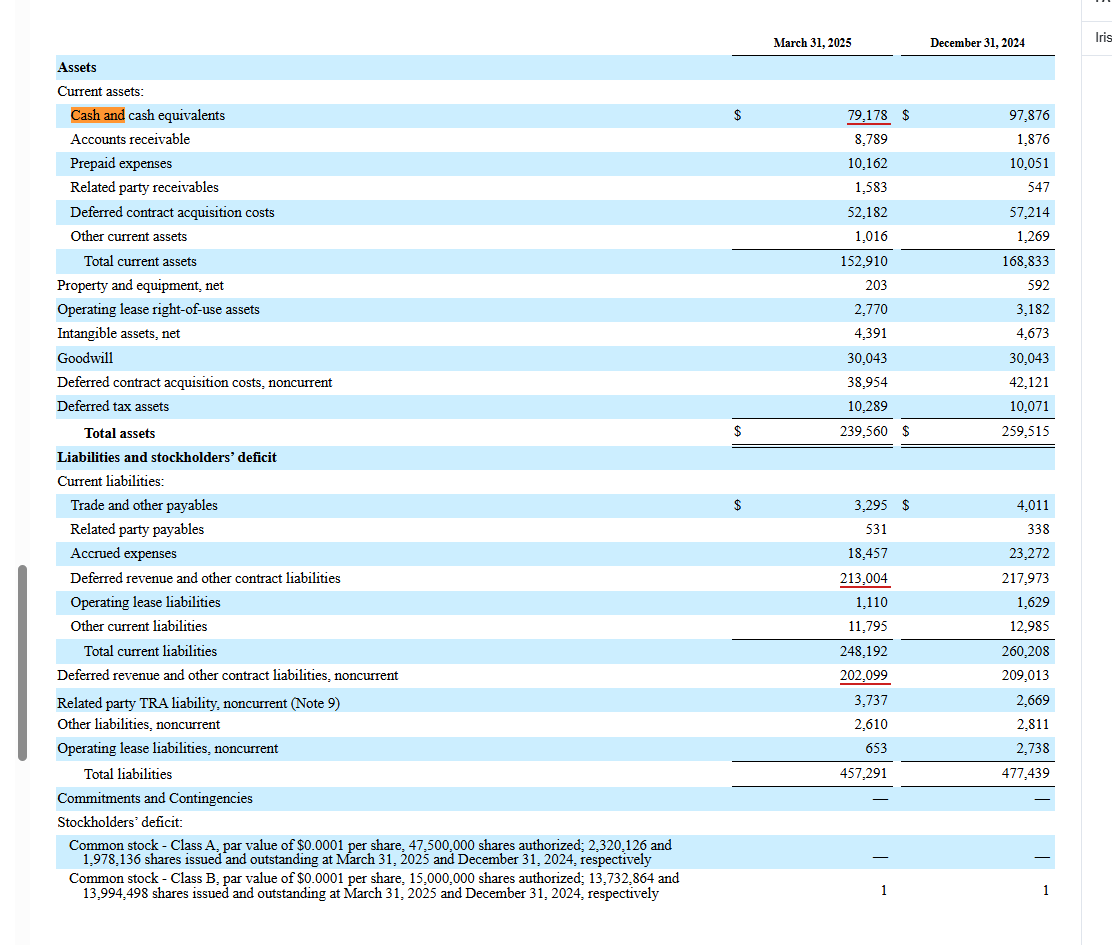
79 million cash - 457 Million Total liabilities + 415 million Total deferred revenue = 37 million dollars net effective cash.
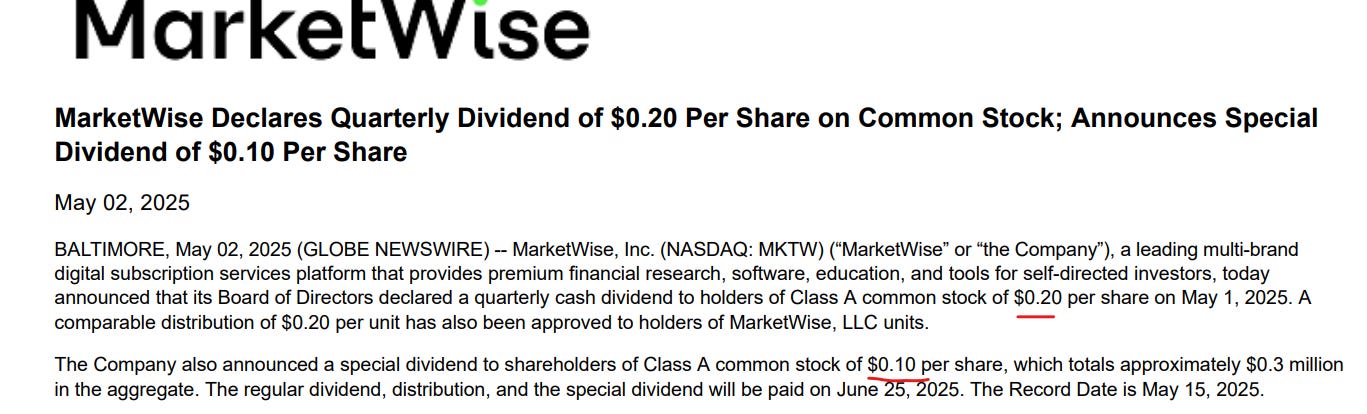
Now the company had 97 million dollars in cash in Q4 2024 but it reduced to 79 million due to some initiatives that management took to instil shareholder confidence. For instance, a 10c special dividend on top of a 20c regular dividend:
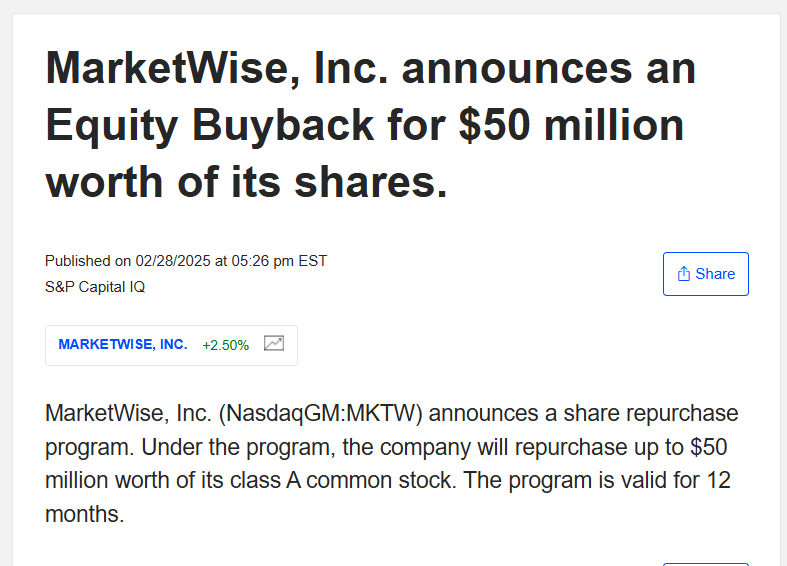
And even more impressively, a 50 million dollar buyback authorisation:
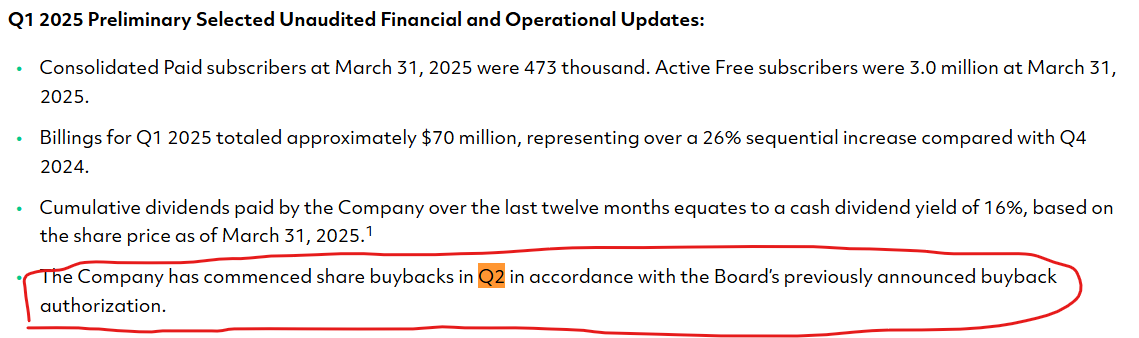
The best part is that management disclosed that they commenced repurchases in Q2 2025:
We think this is a great decision, because one of the few things that can bridge the valuation gap between a ‘value‘ company and a reasonably priced company is enhancement of shareholder value and improving capital allocation. So, when you take a healthy balance sheet enhancing shareholder return through buybacks along with growing billings and a potential for strong revenue and earnings, you get a buy opportunity!
Mild insider-buying by the CFO:
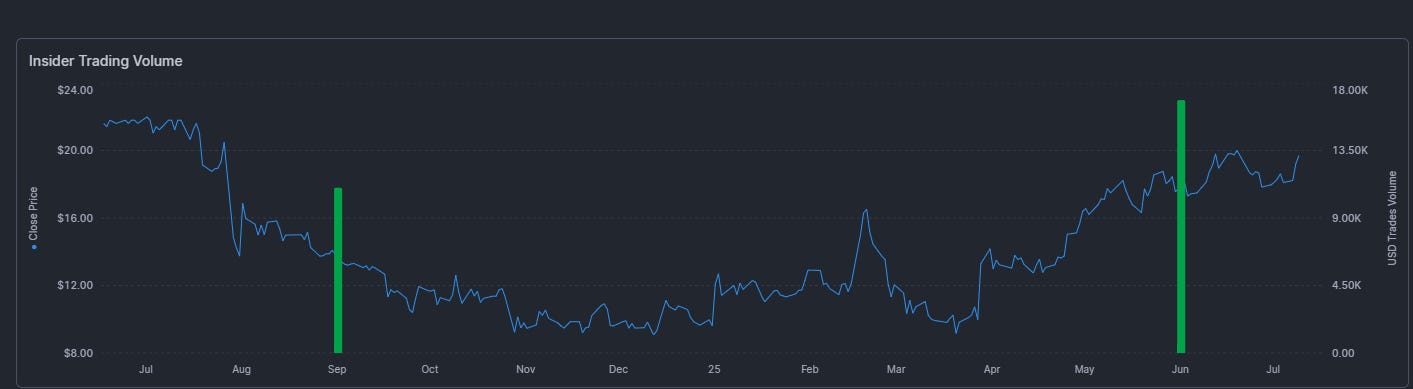
The insider buy by the CFO is just a 16k buy, but it isn’t nothing, and we thinkt hat him buying this amount in such an illiquid stock trading about 300k USD a day is a good enough vote of confidence to us
How we are playing this:
We plan on buying and selling at around 25-30$, depending on how the rest of the portfolio is doing. If the market has a bad reaction to earnings, we will study it and put out our own interpretation of the earnings and revise our outlook based on what is being reported, and close our position if our thesis is proven invalid in any way.
By reading any of our posts, you agree to do your own due diligence before making any investment decisions. You agree that the authors of this publication are in no way responsible for your investment decisions, and are not liable for any of your possible investment losses, and you also agree to acknowledge that we are do not guarantee any accuracy in our research. You agree to also not proceed with any legal action against us.
The authors of this publication do not give any buy or sell recommendations and do not ensure any correctness to our claims or findings. Under no circumstances would you hold the authors liable for any investment losses. One should assume that any sentence or statement in our posts can be inaccurate and factually incorrect and should not influence anyone’s investing.
Sincerely,
Ragnarok Research
Isn't SubStack disrupting this type of research? Are you not direct competition? 10 per month vs whatever these guys are charging? Is any of their stuff actionable?... Bearish stuff buy gold etc etc...
i heard there's this thing called chatgpt...