

MNDY is a project and workflow management software made for enterprises and has been punished by the market for fears of AI taking its lunch, with shares having fallen 70% in the past year:
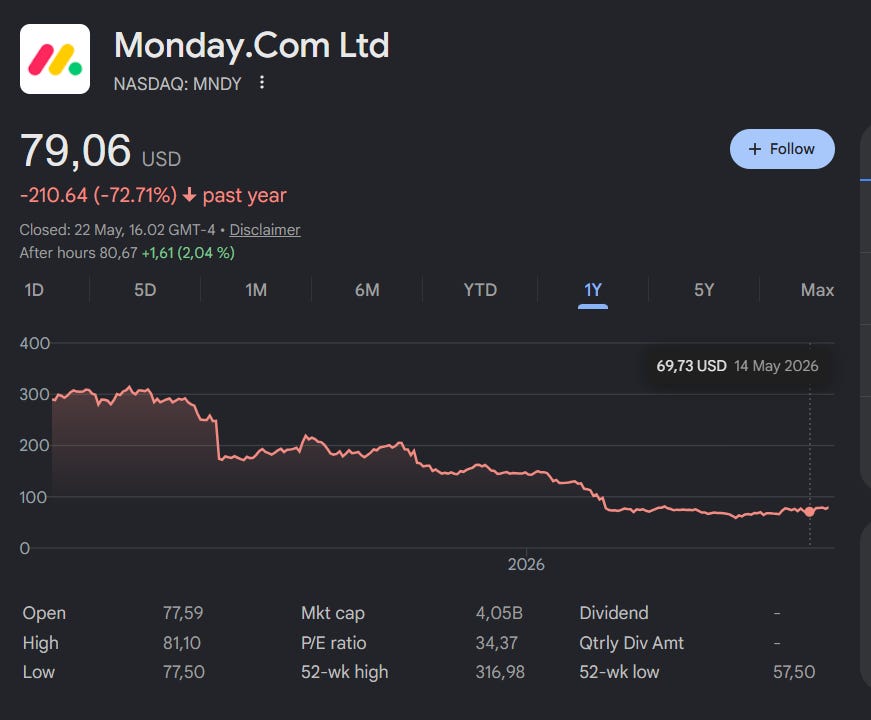
It now trades at a multiple of 2x EV/Sales, a pittance for a SAAS stock
Summary:
Analysts and equity research reports are under the impression that the rise of AI will take away Monday’s moat and its existence as a workflow management software for enterprises.
Analysts model a severe growth deceleration in revenues in the next two years, and we think that MNDY’s 1Y -70% share price performance and current valuation is pricing in a future of 0 terminal value and existential fears
Our research indicates that it is more likely that MNDY’s growth accelerates in the next two years because of the rise of agentic AI
The same way people thought AWS would kill SAAS businesses(but instead strengthened it), we think agentic AI deployed by enterprises will depend on workflow/project management solutions such as MNDY. MNDY has gotten something of a first mover advantage and has made its applications compatible for AI agents to be run by.
This is a stark contrast to analyst models, and while our analysis does indicate a chance that AI does kill MDNY’ s business model, we think that the current valuation reflects that the market prices that possibility at about 100%, while we think it is more like 30%.
What the street thinks
Analysts are under the impression that MNDY will go through a rough growth deceleration due to AI eating up their lunch. As per Guggenheim’s recent analyst report, large customers of MNDY are certain that there are no short term displacements in the contracts MNDY holds, but the long term remains uncertain:
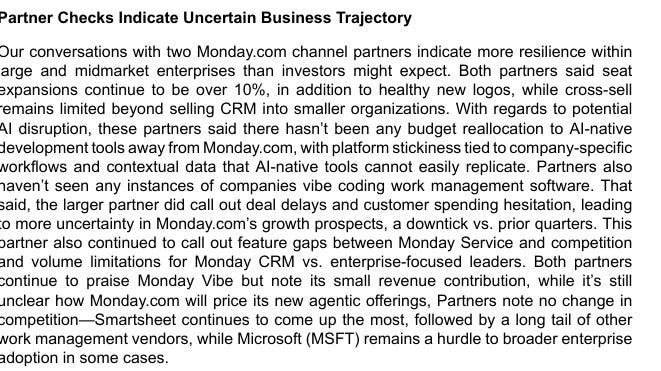
As such, Guggenheim is projecting a 19% and 17% YoY Growth respectively for MNDY revenues. This problem of investor pessimism was exacerbated by a CNBC video where MNDY was ‘vibe coded in 15 minutes’ using Claude, further depressing MNDY’s valuation:
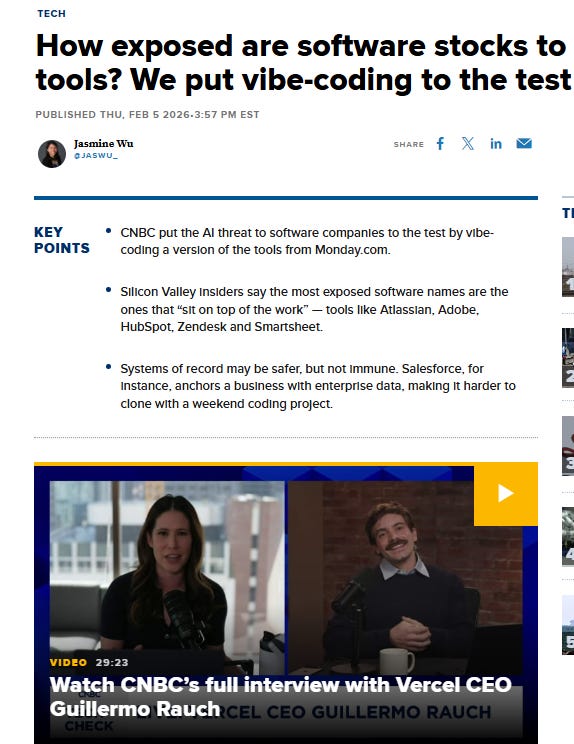
The untrained investor may look at this interview with shock and sell his MNDY shares predicting a SAAS doomsday as they fear AI will someday take MNDY’s lunch.
What we think
MNDY is a state-of-the-art workflow management platform trusted by thousands of customers. An impressive thing about MNDY is its high switching costs. While this does not translate to improvement in revenue growth rates, it still does well to call out the stupidity in MNDY’s stock dropping by more than half.
We spoke to a [small] MNDY customer, and they expressed that while they don’t have plans to switch out of MNDY anytime soon, it would be a huge hassle even if they wanted to.
This is because of how deeply rooted MNDY’s platform becomes in a company’s infrastructure, with switching to other platforms needing external platforms such as movebot or outright paying developers to transfer the APIs to other platforms securely. Larger customers with complex workflows would struggle even more to migrate, exacerbating MNDY’s ‘moat’.
However, the primary reason we think that MNDY shares should command a little bit moore of a premium valuation is a mere probability exercise:
The market, as per us, is valuing MNDY as if it has about a 90% chance of terminal risk, due to it trading at low valuations at 2x EV/sales, while normally SAAS trades at 4x. While this is due to fears of AI adoption, we will prove below how the possibilities of these materialising is way lower than what the market expects
Agentic AIs, when deployed by enterprises, will need a co-ordination layer. Enterprises will never ever just give up the whole company’s operations to AI; it will be a collaboration exercise between humans and agentic AIs. We think MNDY stands to gain as an integral collaboration layer.
MNDY is moving on to a subscription + consumption based hybrid pricing model, where the vanilla MNDY’s uses will be accessible for the same per month pricing,k but AI agentic usage will cost extra. This causes MNDY to potentially gain revenues from existing and new prospective customers, as the chances of existing customers switching out en masse are extremely low, especially if they are large enterprises.
Hubspot CTO essentially validated our thesis that AI will indeed need a co-ordination layer(although he might be a little biased)
The market is punishing MNDY and other SAAS names because of fears of AI adoption and displacing MNDY. Moreover, that little stunt and CNBC where the hosts vibe coded a MNDY clone doesn’t mean anything. I could make a react.js clone of facebook but that doesn’t mean my application will displace facebook: Merely because facebook already has embedded users.
Moreover, IBM Recently published a paper called “The blueprint for agentic operations: How to build an interconnected enterprise”, clearly stating a need for workflow managers:
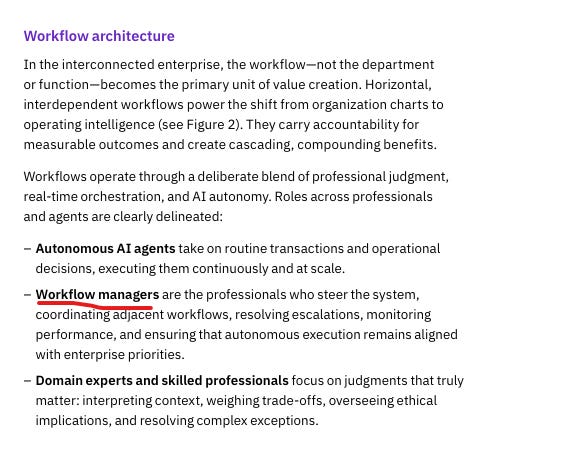
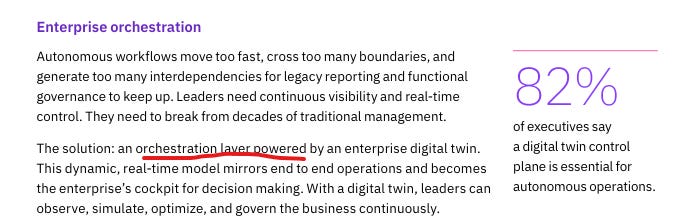
The main takeaway should be that if enterprises do really want to use Agentic AIs in a meaningful way(which is clearly what the market is predicting will happen with MNDY’s depressed valuations), an orchestration layer as a governance tool and workflow management is absolutely essential
Moreover, the idea above of a ‘digital twin’ already exists in MNDY’s roster:
So, therefore, with the apparent need of an orchestration layer and a digital twin, we think that the market is understating MNDY’s potential importance to enterprises for driving widespread agentic AI adoption.
The beauty of MNDY that it has agentic AIs enabled in its platform. It has the capability to let external agents (such as manus) as well as agents hosted in the platform to use the workflow management platform. This pivot into an ‘AI Operating system for enterprises’ is what makes us bullish on MNDY.
Moreover, something we(and the CEO of MNDY) can agree on is that vanilla SAAS pricing models are dead. MNDY’s CEO shares the same view in this podcast he did:
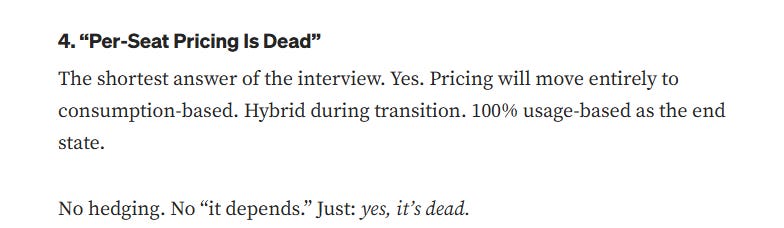
We think this is the step in the right direction. Given that right now, MNDY’s pricing is hybrid, enterprises will likely use MNDY’s agentic AI offerings at some point if the threat of AI is truly real. This should be tailwinds of some sort to MNDY, as a new revenue stream should be created from present customers as it is unlikely a huge amount of them will switch out to other platforms, and instead would opt to use MNDY’s AI offerings, in addition of course to future prospective revenues.
While this might be a biased take, HUBS CTO purchased about 1.8 million dollars in HUBS shares, and this was his thesis:
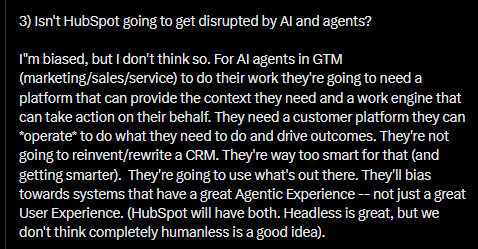
Link to whole tweet here. We think Dharmesh knows better than us and more than most people. He here is talking about the same orchestration layer we read in the IBM paper, and we think experts hinting at the need for MNDY’s offerings(indirectly) is bullish, and while AI risks might be real, the risk-reward is in might be in our favour.
Final checks before pulling the trigger
Talk to competitors how good MNDY is
Will enterprises truly adopt orchestration layer?
If orchestration layers are to be adopted, who is gaining the most? HUBS? ASAN?
Any subscriber with expertise or insights on this name, please email me.