

So before I indulge all my future readers(I have 0 at the time of writing lmao) to my bad fundamental analysis thesises and stuff like that, Lemme talk about my first volatility arbitrage (dw, it was not a 'smart' trade at all, prolly luck tbh)
Volatility arbitrage is essentially spotting a mispricing between an option’s IV(Implied volatility), and its RV(Realised Volatility)
Now, I am broke(im 15, what do you expect ?)
I aint got the bread to get PredictingAlpha or market chameleon to plot IV and RV.
But… I can code.
I stumbled across alphaquery.com, a service which gives IV and RV data (very limited, and data is given fully only for ‘famous stocks’, not unknown stocks like BioTech)
Now, I coded a very simple python script to scrape the data from alphaquery to a csv file, and plot it locally using matplotlib.
Nice !
I wrote the program to plot IV/RV values over time. It looks like this:
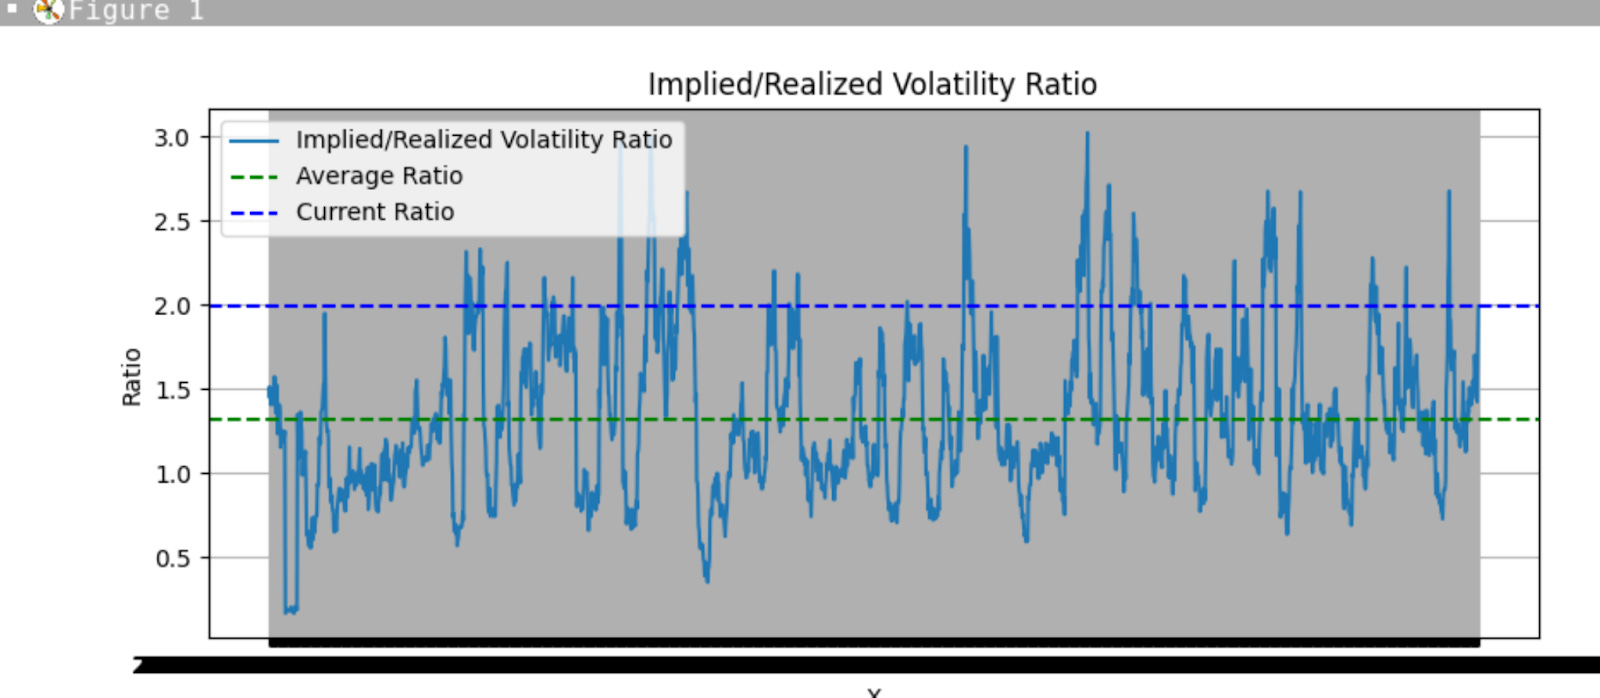
This is IV/RV values for UVXY.
Now, if you sell options and hedge away all directional risk, your profits are based on the spread between the IV and subsequent RV(also obv its great to see theta working for you)
Now, I started hunting places for this spread is high relative to its mean.
One good example is UVXY tbh, but I would wait until the spread is even higher ig, or when its trajectory is already sloping downwards
GOOGL
I found an opportunity with googl stock options for arbitrage
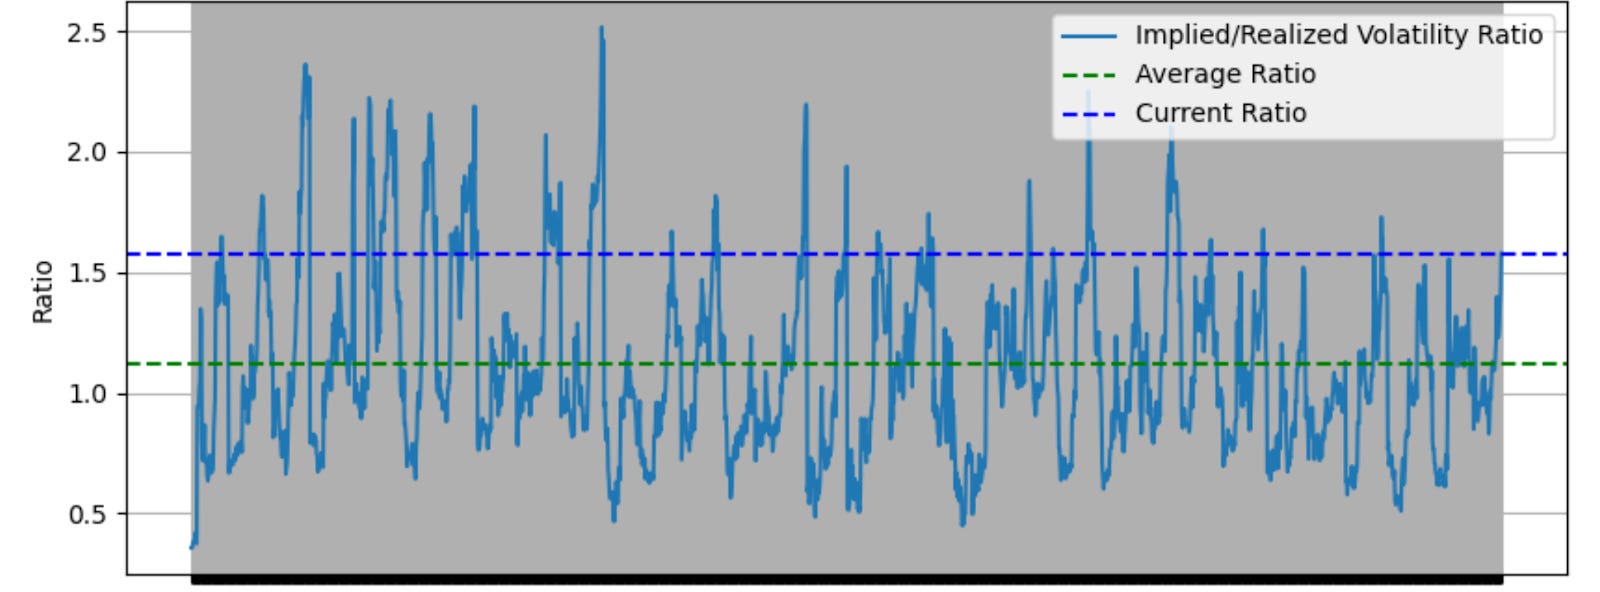
The IV/RV value was pretty high, and always seemed like it would fall immediately after it started its downward descent.
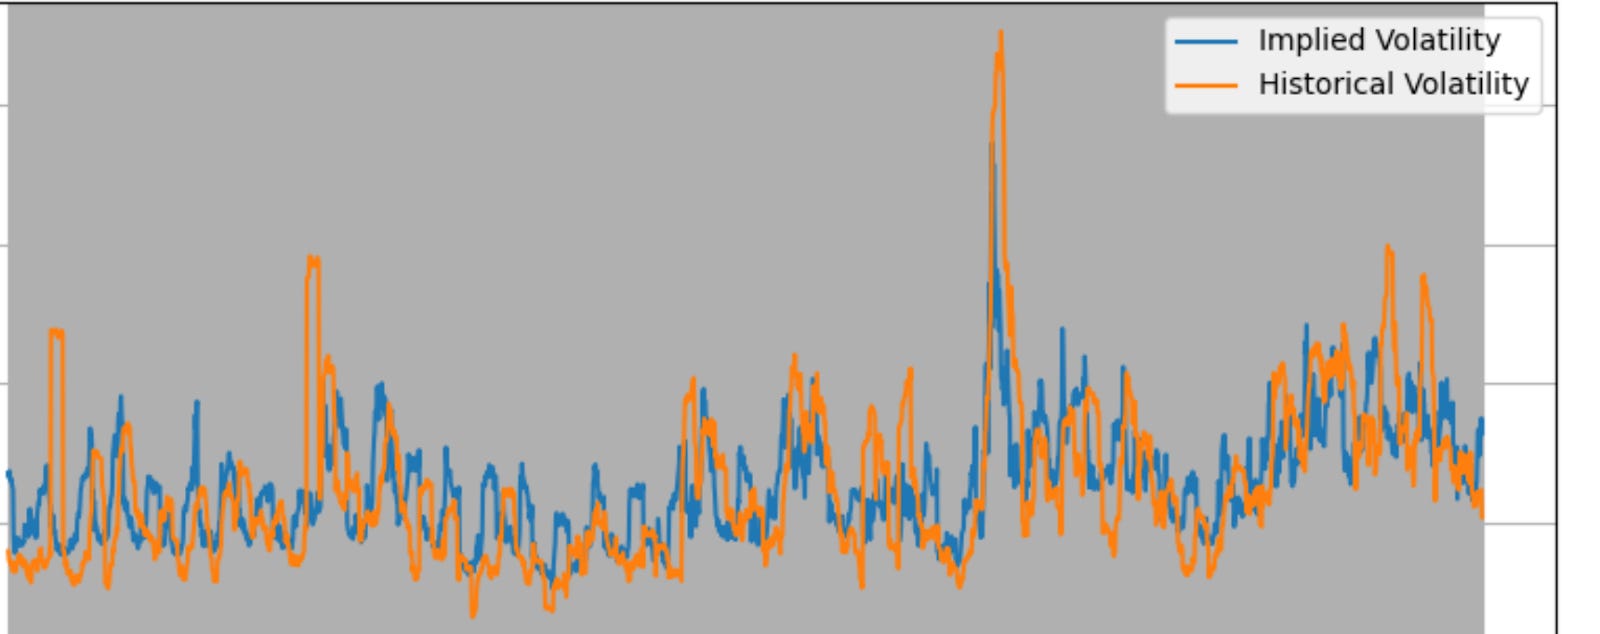
At the end of the graph, we can see there is a pretty big mispricing of volatility. In the past, this degree of mispricing is mostly followed by drop in IV.
So, I decided to sell a straddle (Probably should do a lot more DD than this but… eh… as i said, im a bad trader and i accept this)

Soooooo it didnt backfire YET ( it will prolly, we still have 27 days to go, imagine what would happen if googl just announced ‘GOOGLE HEADSETS’)
All in all, bad trade due to bad due diligence,but MIGHT not end that bad due to theta.
Things I should've done(reflekshuns):
I had decided to sell a straddle 30d away. For the safer side, I should've sold shorter-dated options since theta is high, and the chances of a big market move destroying our position would be low. will do next time. my spoilt ass was attracted to the big premium, and used only 30d options since the data I parse from alphaquery is 30d implied and historical volatility.
Other ideas:
1) Im looking into IV correlation trading between SVXY and UVXY(basically inverses of each other)
2) Indian stock market has some interesting qualities since NSE(national stock exchange) gives a variety of indices to trade (like nifty 50, nifty bank, nifty low vol, nifty small-cap 250) and i can see some arb opportunities