


When people first get introduced to option pricing, it's primarily the Black Scholes Model, or Put-Call Parity.
I feel that the Black Scholes is slightly overused, so I’ll just write about PCP.
So, a few gamblers high on caffeine found an equation that describes the relationship between a European Call and Put option, which may give hints of which is under or overpriced.
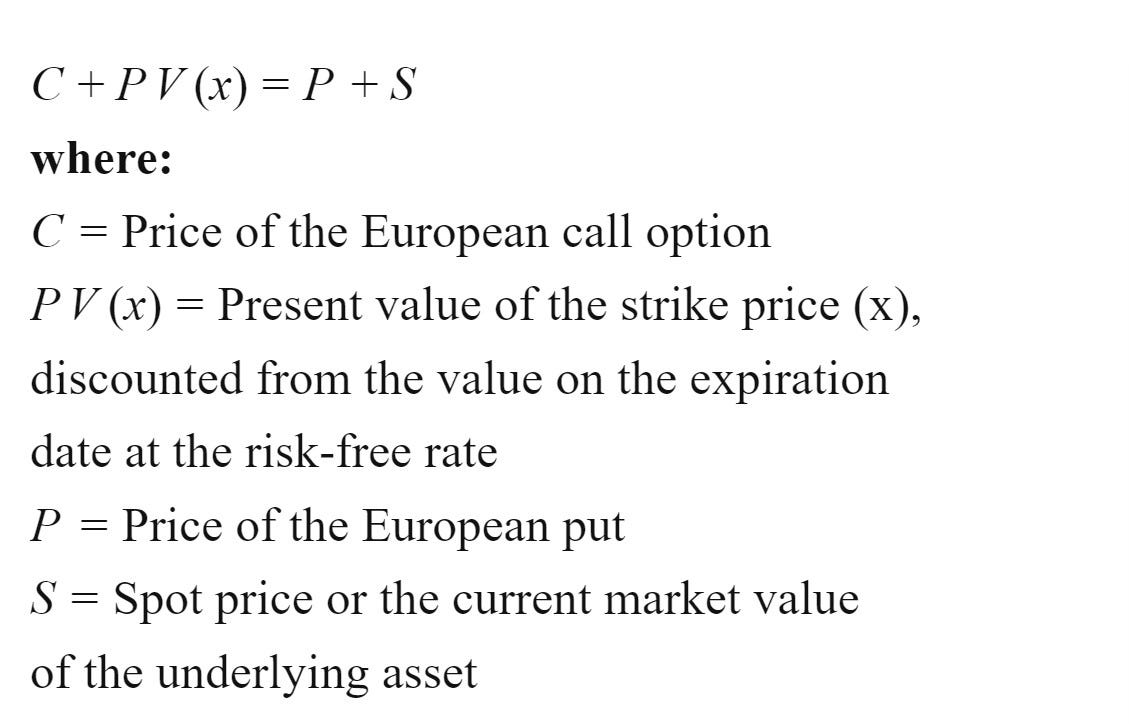
(Investopedia)
Right from the get-go, I can recall a few instances where I thought I would find price discrepancies. For example, the VIX, at the time of publishing, is an instrument for hedging against recession, and, of course, speculation by the gamblers.
Guilty, as charged
So, let’s calculate the equation for the VIX.
Call Price = 3.7
Strike Price = 17
PV(x) = Strike price/(1 + risk free rate)Time to expiration in years
Put price = 1.51
VIX Spot: 17.3
Time to expiration = 0.25
Risk-free-rate: 0.426
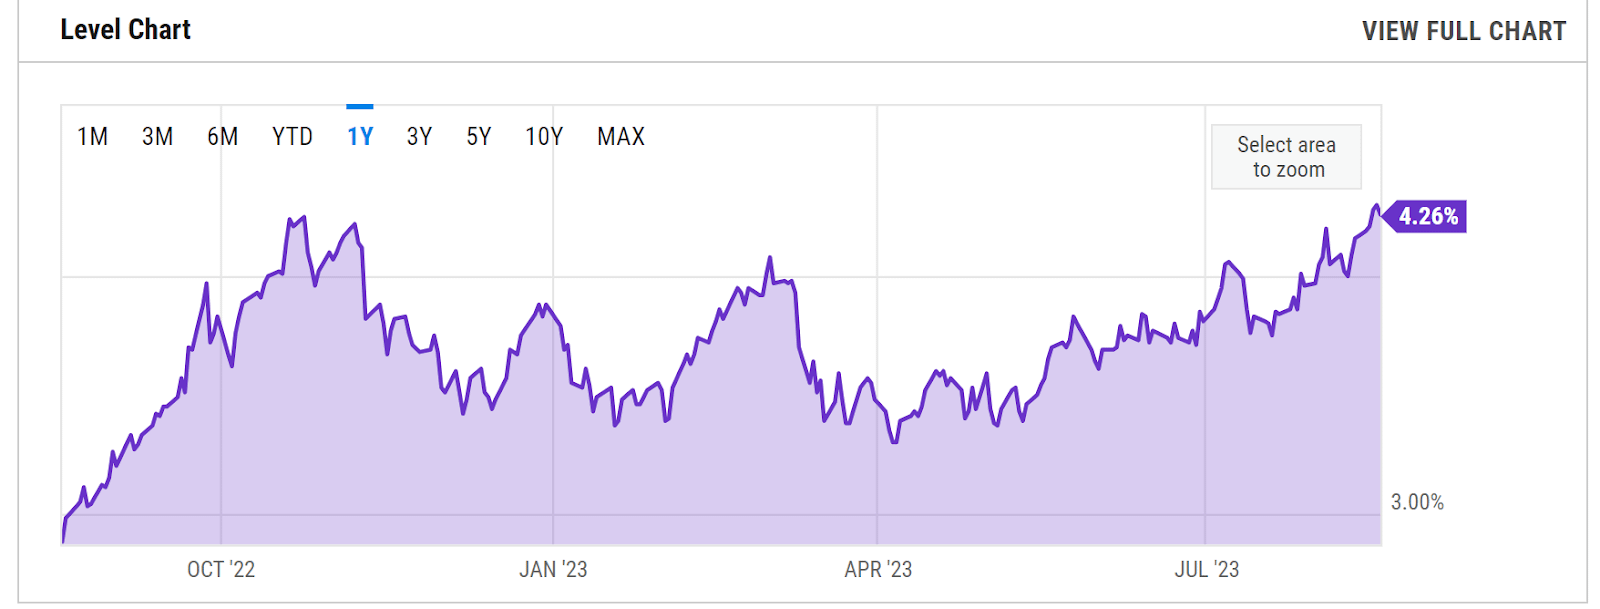
Now, let us calculate both sides of the equation given above:
PV(X) = 17 / (1 + 0.426)^0.25
PV(X) ≈ 16.7571
C + PV(X) = P + S
3.7 + 16.7571 = 1.51 + 17.3
20.4571 ≠ 18.81
This means that there is an arbitrage opportunity, since the left-hand-side does not equate to the right-hand side. But, then again, I think to make it riskless, you will need to buy the RHS, and sell the LHS. Buying the RHS means you will need to buy the VIX, which isn’t possible, so we look for other opportunities.
Let’s look at this calculation for SPX, because I imagine there is a lottt of hedging pressure, speculation, etc, with the recession rumours and all that.
We have:
Call: 92.5
Put: 73.85
PV(X) = 4370 / (1 + 0.436)^0.08333333333
PV(X) ≈ 4360.876
S&P E-mini Spot: 4.380,00( Since we can’t directly buy SPX, we shall adjust with the futures)
So, let us calculate the equation:
C + PV(X) = P + S
92.5 + 4360.876 = 73.85 + 43800
4453.376 ≠ 43873.85
Well, this means that there is a price discrepancy, probably caused by fear of a recession or whatever.
ORRR
Our calculation is outright shit, and using the price of futures for spot was a huge mistake … But eh what can you do right ? Just to be safe, let’s calculate the numbers with SPOT SPX:
4453.376 ≠ 43771.56
Ok, we are still good, I guess … Still would argue that it is very probable we messed up somewhere.
But, now that we think that we have a market discrepancy, how do we exploit it ? We buy the cheap side and sell the expensive side
Steps:
1) Sell the call for 92.5 per contract (Sell 100 at a time)
2) Borrow money for the time period with interest being the risk-free rate for that period (selling debt ?)
3) Buy a put for 73.85 per contract (buy 100 at a time)
4) Sell SPX futures