


The NVDA Paradox
You know the thing in physics where light behaves as a wave and a particle ? And you have no idea why or how because you have 10 braincells?
Yeah, I relate…
But, this idea reminded me of a Nvidia stock, since I have seen a lot of people(very smart ones) give amazing justifications to their bullish and bearish outlooks for the stock.
That leaves us, the dumb people with no opinions.
So, let’s discuss
Exibit A: The bulls
This is, in a way, a no-brainer. With all the Generative AI fiasco, NVDA has risen by a lot, since their products are essential for the AI industry in general. Nothing runs without these procoessors. So, the AI boom obviously meant a boom for NVDA, resulting in this:
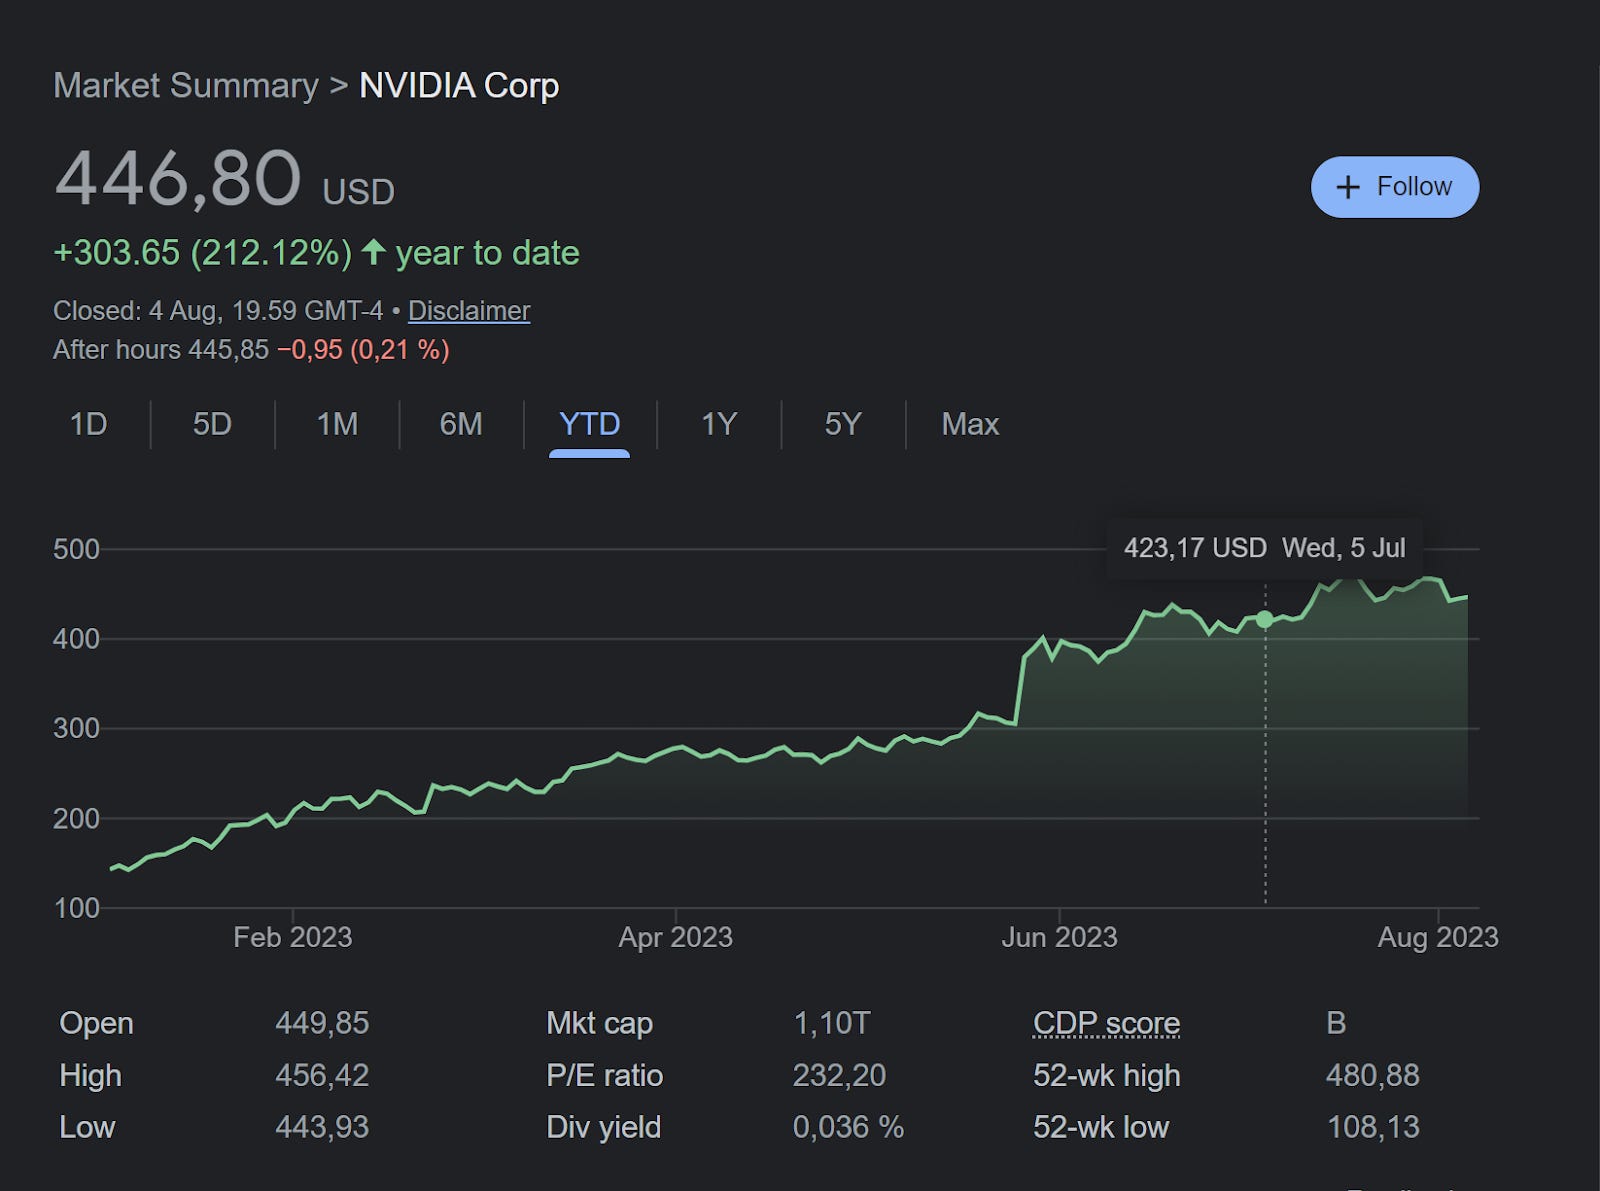
That is insane… Imagine shorting that and you just see it edging higher and higher.
As of now, Generative Artificial Intelligence is limited, and is not in access to everyone.
But, imagine when it is.
Imagine all the AI data centres needing these processors. The demand would shoot right up, and that would be just insane for Nvidia.
Imagine Nvidia’s earnings. That would be explosive. The fact that its market cap is 1.1T, and there is a chance that it’s just getting started? Goddamn that’s a huge buy.
Even analysts across wall street love this stock. I mean, can you blame them really ?
AI model upgrades demand more hardware. With NVDA controlling 80% of AI processors market, you can deduce that NVDA would benefit from this phenomenon.
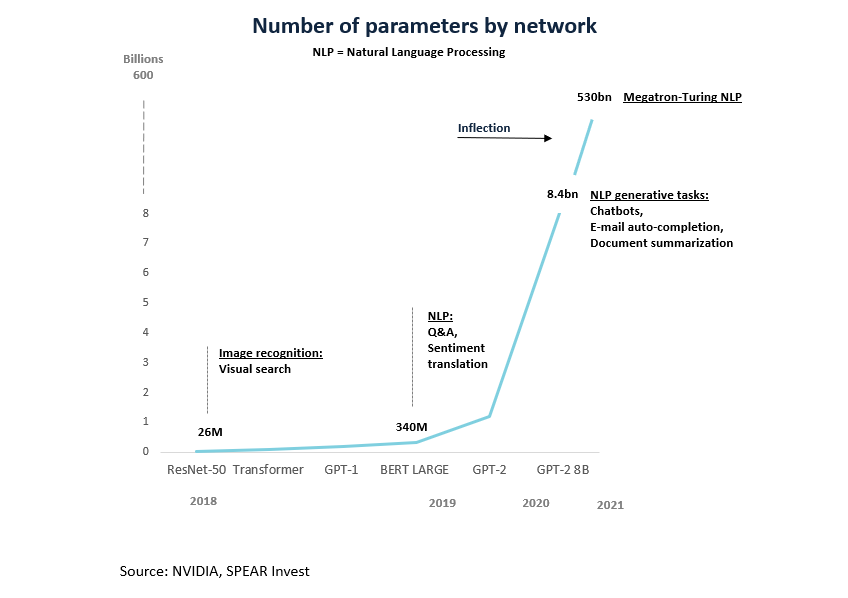
The model upgrades are growing exponentially as a matter of fact.
I’ve read predictions that NVDA’s processors will be the backbone of autonomous driving. Elon even said that he’ll be mass ordering shit from NVDA.
Looks great for the business doesn’t it ?
But, what about the stock?
Exhibit B: The Bears
Both the bulls and the bears agree that NVDA’s business is a money printer, but the stock ? This is where the disagreement comes in.
The bears think NVDA is overvalued. In fact, Ashwath Damodaran, the dean of valuation himself, thinks NVDA is overpriced.
When Damodaran speaks, you listen
But, let me lay out my understanding of NVDA’s valuation.
NVDA’s Price to Earnings ratio right now is 232, with the stock at 446.
That high a PE ratio is crazy.
Now, tech stocks on average have a PE ratio of 25-30.
Just to prove me point of how much speculation is baked into NVDA, I’ll perform calculations by assuming that NVDA’s PE ratio will revert to 30.
Assuming NVDA’s stock remains the same, and assuming NVDA’s PE ratio should revert to 30, that can mean 2 things:
- Stock falls by almost 8 times
- Earnings grow by almost 8 times.
Well obviously it doesn’t exactly work like that, but it’s my understanding of NVDA’s crazy valuation.
Crunching some numbers as per this video, Assuming we hit NVDA’s guidance of quarterly net income of 4.15B then we hit an annualized figure of 16.6B
So, even if NVDA hits the absurdly ambitious guidance number(for reference, the last 12-month net income is 4.79 Billion), we have a PE Ratio of 60.
So, to sum it all up, in order for the stock to be sustainable by assuming the PE ratio will revert to 30 over time, Annualised earnings should grow to about 32 Billion, about 8 fold from its current value, and 2 fold from its quarterly guidance annualised.
Is this possible? It is very hard to say.
When investors pile their money in NVDA, they are betting that a Trillion dollar company can grow its business many times over.
This would've been more probable for a small-cap stock… But NVDA ?! A trillion dollar company growing its business many times over ??!! Ehhhh.
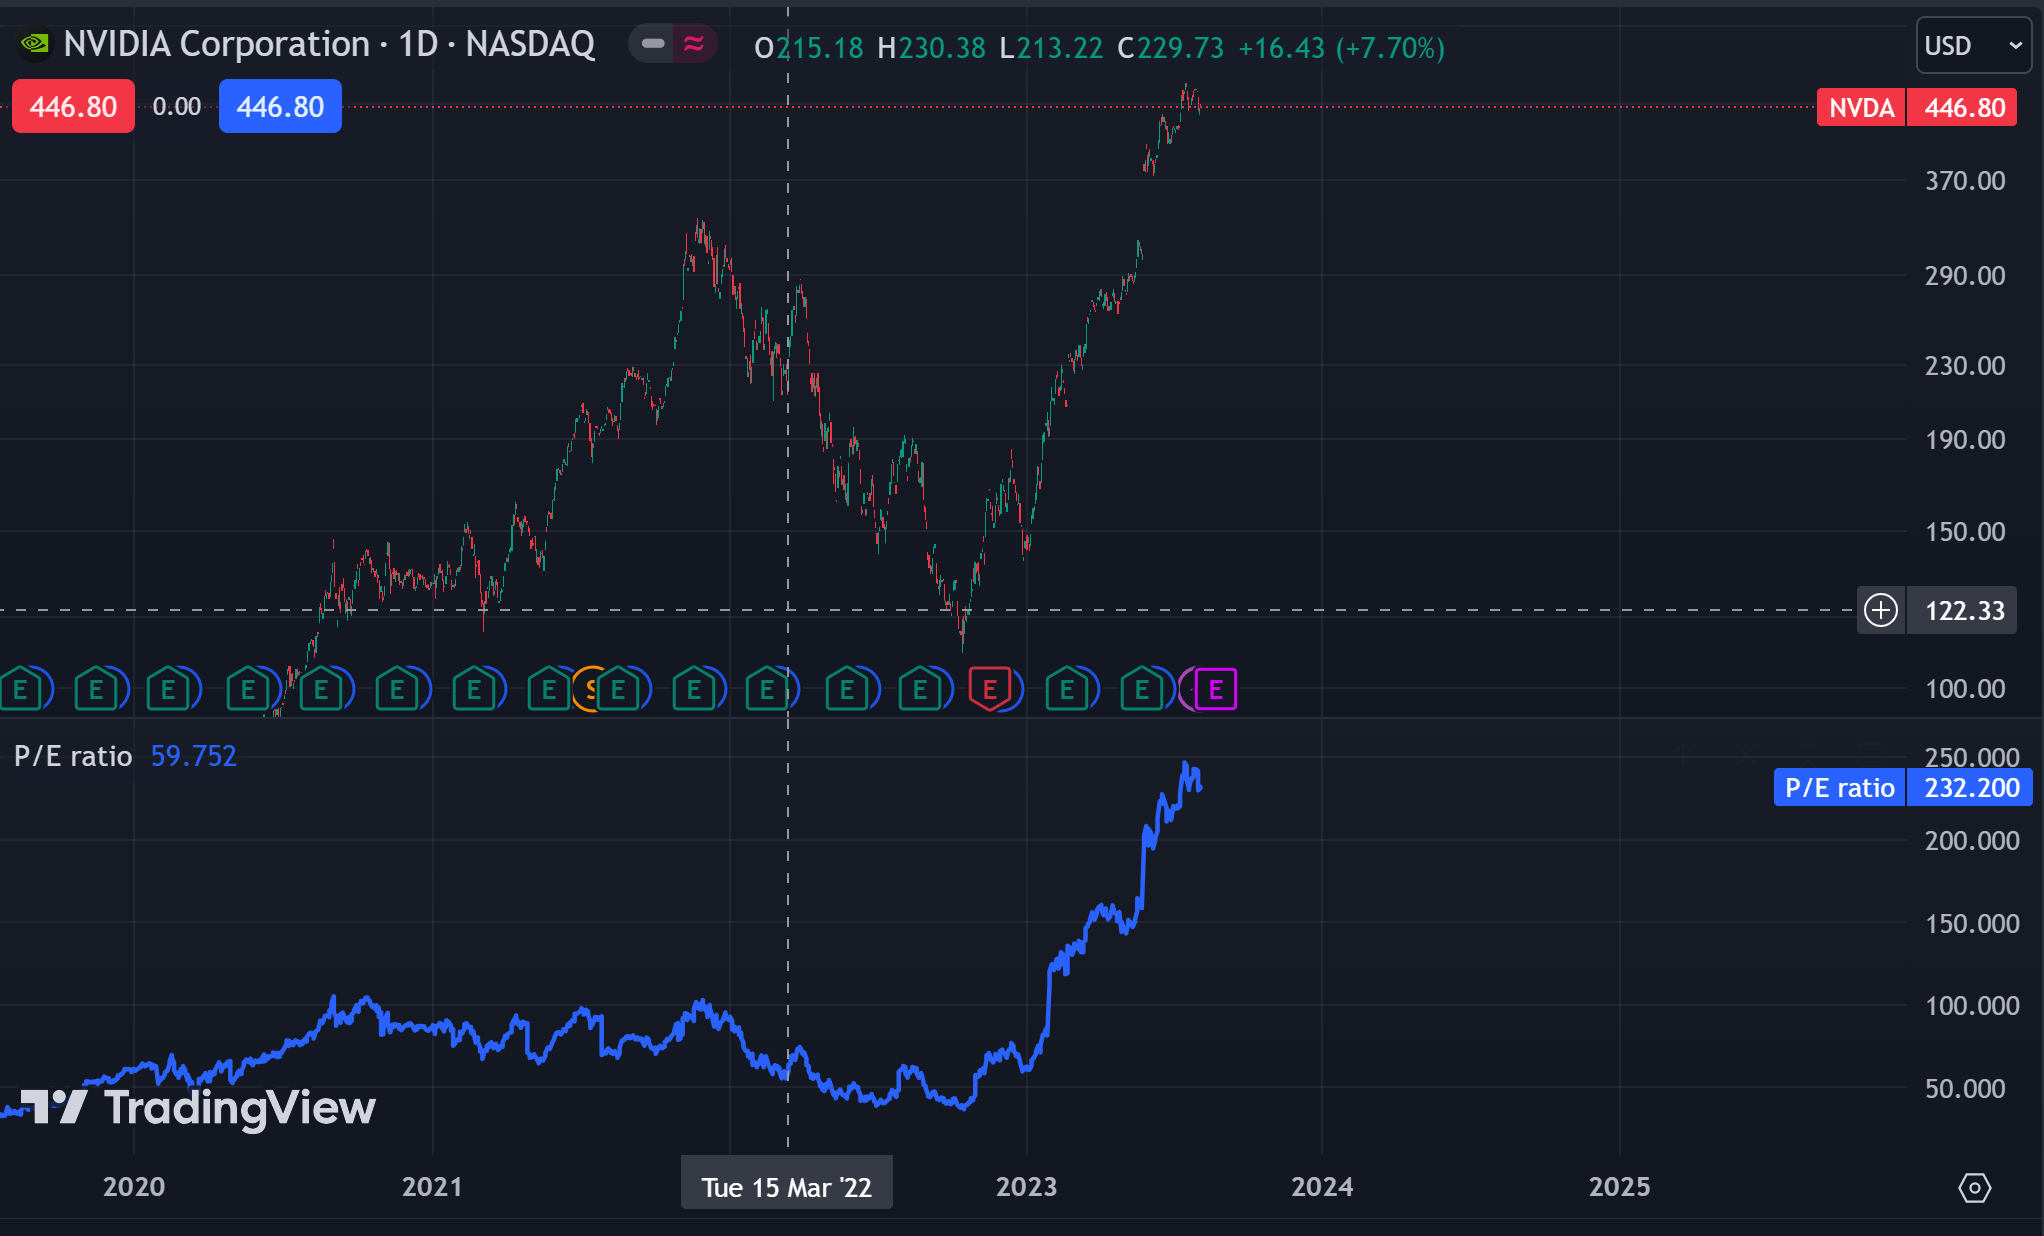
Past examples of absurd valuations
Let’s look at Tesla:
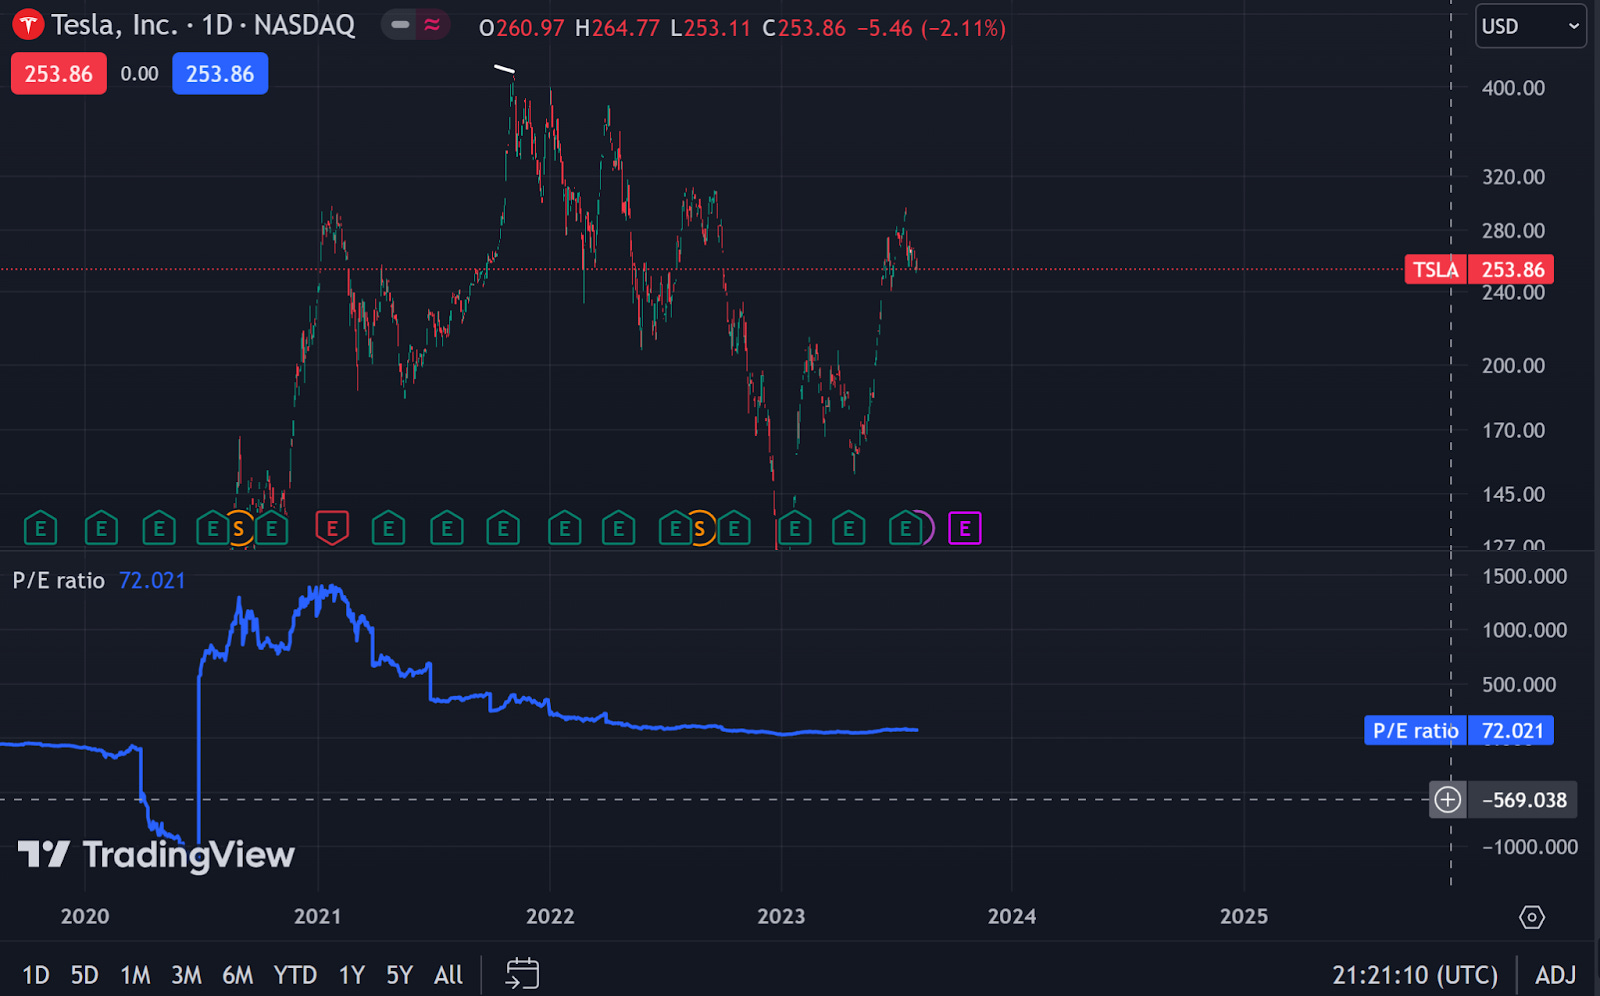
It had a PE as high as 1.2k once… totally insane.
This stock desperately needed a correction.
But… when ? A lot of people knew Tesla had to come back down, but they lost money since they could not time it correctly.
Notice a white mark on the chart ? This was when Tesla entered a trillion-dollar valuation. That is also the time that Tesla started declining.
Is there a mechanism that the market understands that a company cannot its business many times over after it hits trillion-dollar status ? IDK.
I could definitely see in all trillion-dollar companies that growing earnings by huge margins is extremely difficult, cuz the company is huge already.
Maybe this effect applies to NVDA ?
Conclusion:
I can interpret it the following way:
1) NVDA has a great business and MOAT
2) NVDA has an overvalued stock, and it may decline
3) Both of these 2 possibilities can co-exist
NVDA is going to be a huge AI player. That’s for sure.
But the stock ?
I think the market won’t crash, but will correct aggressively.
We will prolly see the maturity of a hugely bullish growth stock, to a GARP stock(Growth At Reasonable Price)
We can already see it happening since momentum has slowed down.
Should you listen to me ?
Hell, no.
I’m a 15 year old teenager who doesn’t know what the hell I’m doing. I’m just having fun here, mate. Nothing more.
I can be dead wrong, or I can be sooo right for the totally wrong reasons.
After all, would you trust a kid with gambling issues ?
Prolly not.