

Executive Summary
TransAct Technologies(TACT) IPO’ed on the capital markets on August 22nd, 1996. Thirty years later, the shares of TACT trade at roughly $5/sh, below levels the stock reached in the late 1990s. A shareholder who invested in 1996 and held for three decades has, in share-price terms, essentially nothing to show for it.
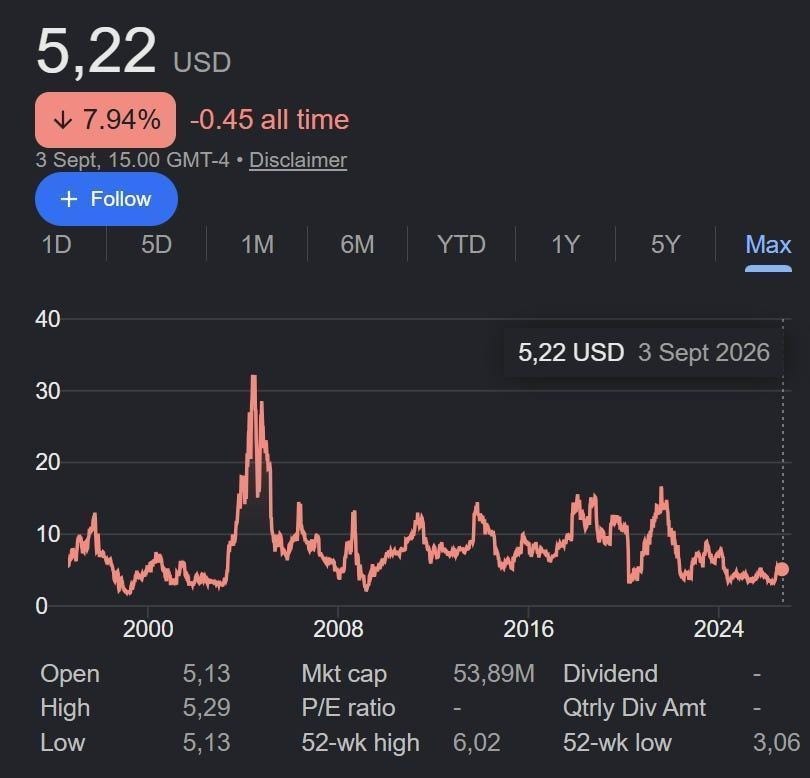
Even though TransAct now houses a litany of undervalued and strong assets, the share price hasn’t reflected this reality, in part, we believe, because of what we believe are failures of board oversight and capital allocation. Therefore, we are releasing this piece demanding for changes on the board of directors to address some blatant conflicts of interest and governance failures, as well as pushing for a different strategic review approach than the one currently undertaken by the board:
The board’s current value generation lever is to explore the sale of their casino and gaming segment. Typical value generation moves are the selling/divestment of the non-core or even lossmaking divisions of the company. In this case however, TACT has hired an investment banker to seek strategic alternatives such as selling its core, cash generative casino business, effectively leaving shareholders with the Food Service Technology segment, a segment we believe to be lossmaking, along with corporate overhead and, in our view, limited standalone growth prospects
Therefore, the action that is in best interest of all shareholders is to prioritise the immediate sale of BOHA!/FST segment above the sale of Casino via the hiring of an additional investment banker to carry out a strategic review of this segment. We think it is extremely crucial to facilitate the selling of the FST/BOHA! segment either first or at the same time as Casino rather than after because the negative cashflow and the corporate overhead of a standalone public company will run the company to the ground if FST is left for shareholders to bag-hold.
Moreover, even if the board does intend to sell BOHA! After the casino segment’s sale, the negative cashflow shortens the runway the board has to execute a sale while still preserving value and in the worst case can result in value destruction if the board can’t find a buyer for BOHA! Therefore, to hedge against the risk of the FST either being unsellable or it being the remainco and destroying long-term shareholder value, we strongly advise the prioritization of BOHA!’s sale first
We specifically ask to hire an additional investment banker so that the two sale processes can have 0 overlap with each other in case both the companies need to be sold: if the board auctions the company as a single piece, the highest bidder would have factored some amount of conglomerate discount. However, due to the unusual separability of the two segments, it should be easy to sell the company in two pieces, or more crucially, sell the FST/BOHA! segment first
We request the cleaning up of certain conflicts of interests and governance failures at TACT: Two of TACT’s six directors, Emanuel Hilario and Haydee Ortiz Olinger simultaneously serve on the board of ONE Group Hospitality(STKS). We believe this can be a breeding ground for conflicts of interests because TACT sells products to ONE Group. The co. ‘s proxy disclosed sales of food service technology products to STKS in both 2025 and 2024. Mr. Hilario is not simply a director of STKS; he is also the President and CEO and his disclosed economic stake in STKS is many multiples of his holdings in TransAct
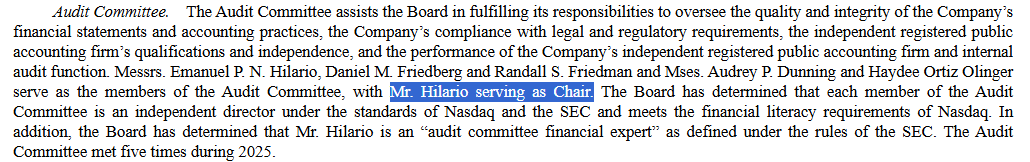
Another example of Governance concern is that the body tasked with policing relationships like this(TACT’s Related Party Transactions Policy) is administered by the audit committee, which is chaired by Mr. Hilario himself: The Chief Executive of the related party whose transactions the committee is tasked with scrutinizing!
Ms. Olinger, who is the chairman of the board with just a 0.3% ownership of the company’s shares outstanding is part of the two-person bloc interlock in which the other company is a customer of TACT. This makes us believe that she is unfit to be the chair of the board. Thus, we recommend that Mr. Dan Friedberg be the chairman of the board because of his substantial 10% stake in the company, allowing his interests and that of the shareholders be aligned and hopefully lead the board to facilitate the immediate sale of the BOHA! segment.
We recommend the addition of one or two directors to the board with deep knowledge of both the BOHA! and casino businesses. We call upon the board to consider Bart Shuldman as we believe that he is the right candidate to execute a quick selling of the BOHA! unit to the right strategic buyer at the highest price, as well as the casino segment since we think his ideas of the company’s future aligns with what is in the best interests of the shareholders. Moreover we also ask the board consider the removal of other incumbent non-incentivised members; Fix the governance problems and conflicts of interests entrenched within the Board, and to refocus the current efforts of a strategic review to sell the BOHA! segment first instead of/in addition to the selling of Casino, rather than vice versa.
Business Primer: TransAct Technologies is an undervalued company trading at about 0.7x EV/Sales
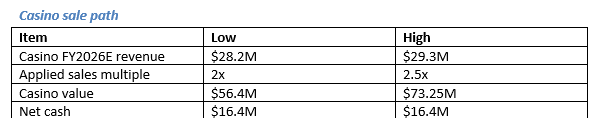
We have exposure to TACT shares because it is a real business with undervalued assets which we value much more than its current Enterprise Value. Here is our base case valuation exercise with multiples we believe are reflective of what strategic buyers would pay for the casino segment:
And these are our valuation tables for the BOHA!/FST segment:
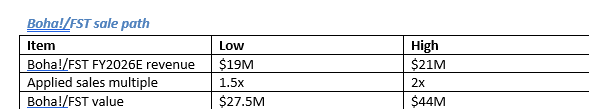
Adding all the back-of-the-napkin valuations gives a blended valuation of the business at 100M to 134M. This represents an 80% to 148% gain in market cap relative to current valuations.
The valuation multiples used above are what we think a strategic buyer would pay for the businesses separately, where they would pay a fair valuation/slight premium to seek synergies out of the businesses. Keeping this in mind, we, the authors of this analysis, think that management and the board have, in our opinion, failed to pursue the value-unlocking moves available to them, and we believe the conflicts of interest and governance failures described below help explain why..
Our stance on what the board should do with the company: Urgently prioritise putting up the BOHA! Unit up for sale via the hiring of another investment banker first instead-of/in addition-to its Casino strategic review to drive an 80%-140% return
Concurrent to our valuation exercise in the first section of this piece, we can clearly see how the SOTP of TACT far outruns the valuation the market is assigning it right now. With valuation gaps this big, the most effective activist lever to be pulled is to sell the businesses to a strategic buyer using the below valuations as a proxy for how much we think it’s worth:
The company is already pursuing a strategic review of its Casino/gaming unit with Bank Of America searching for a buyer. However, if this sale goes through, shareholders would then be left with the FST/BOHA! segment, which we believe operates at a loss and would be left carrying the corporate overhead. While the sale of the Casino business can be value accretive in the short-term, shareholders would be left bagholding an asset the market will likely punish long term. Even in the scenario that the board intended to sell BOHA!/FST segment after the sale of casino, this would mean that the time in between would result in nothing but an erosion in the company’s cash balances because of the new corporate overhead and the negative cashflow- making it all the more dangerous in the case that the board can’t find a buyer for the FST segment.
However, BOHA! can attain a reasonably rich valuation if it is sold to a strategic buyer, as they will be acquiring approximately 21,800 active BOHA! units per the company’s Q2 2026 reporting - which can be an extremely value accretive asset to a strategic buyer. Therefore, we highly recommend that BOHA!/FST segment be put under strategic review under a high-priority mandate and have it sold immediately for about 30-45 million dollars. We ask that either BOHA! gets sold and Casino stays, or both companies are sold under separate, parallel strategic reviews instead of shareholders being stuck with what we believe is a lossmaking segment that would erode the company’s net cash over time.
It is crucial that TransAct and the board hire an additional investment bank to conduct a strategic review of BOHA! instead of the same review for both casino and BOHA!. While the selling of both companies does make it a whole-company sale in effect, offering both unrelated pieces servicing customers at pole-ends of the economy can result in the highest bidder factoring some conglomerate discount into their bid. Therefore, to make sure BOHA!/FST segment as well as the Casino segment reach their full, rich valuations, they will have to be auctioned in completely different, parallel markets.
A great precedent of what we think TACT should do is made of two examples: Meredith and Kaman. Meredith did a simultaneous two-buyer breakup where they sold Local Media Group to Gray Television while the digital business was scooped up by Dotdash:
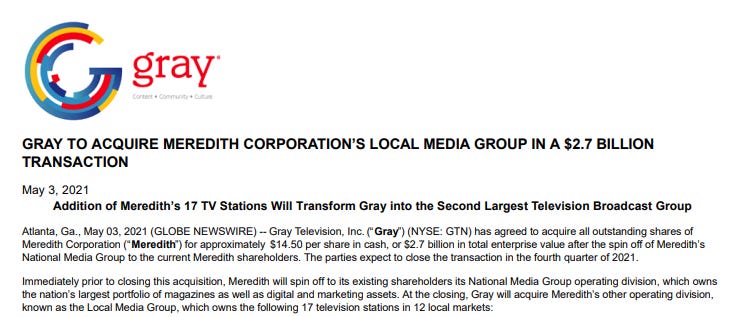
This is what we believe a dual strategic process would look like if TACT did it: Meredith’s break-up and parallel sales returned approximately $59.17 per share in cash to shareholders in total, by our estimate roughly 80% above the undisturbed pre-announcement price.
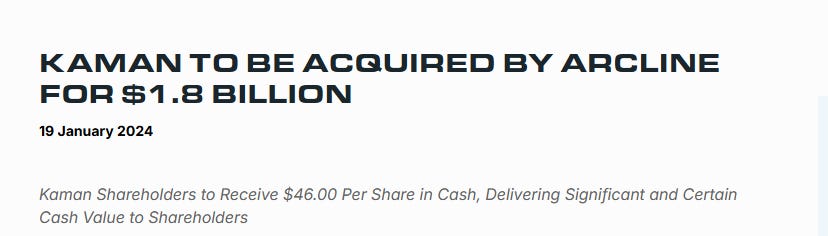
In case that the newly elected board decides that it is better to prioritise the selling of FST/BOHA! First and only then concentrate on the selling of Casino, we believe that if done right, the product of the strategic reviews would look like Kaman: it sold its Distribution segment to Littlejohn in 2019 and then sold the remainco to Arcline in 2024 at roughly a 105% premium to the prior close:
The Casino segment will attract buyers such as JCM Global, Nanoptix, Light & Wonder, IGT and Everi, Sega Sammy, Star Micronics, and Bixolon while the FST/BOHA! segment will attract acquirers such as PAR, Toast, Crunchtime, Restaurant365, Ecolab, Zebra, Brady, distributor tech arms, and restaurant software sponsors. The acquirers come from completely different backgrounds, so the strategic reviews can be conducted in parallel. In contrast, if a singular acquirer such as a private-equity firm approaches the board for an acquisition, they will mark down the assets lower than what they can be sold off individually. Moreover, given how separable the two businesses are because of the complete lack of synergies between them, it is entirely possible to initiate a dual, parallel strategic review for each of the assets
Governance concern #1: The Chair of the board of directors is in conflicted interests to create shareholder value and suffers from a two-person Board interlock
TransAct Technologies has a six-member board of directors:
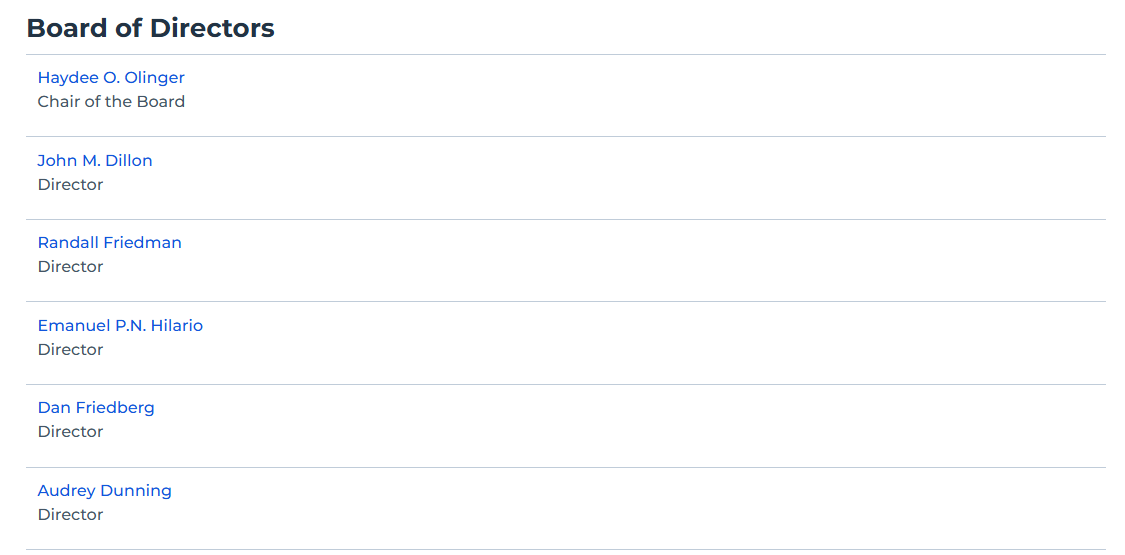
Haydee Olinger: 0.3% owner and the Chair of the Board of Directors
John M. Dillon: 3.3% owner
Randall Friedman: 0.21% owner
Emanuel Hilario: 0.28% owner
Audrey Dunning: 0.19%
Dan Friedberg: 10% owner
Emanuel Hilario and Haydee Olinger together are also board members of another publicly traded company called The ONE group hospitality(STKS). Moreover, their economic stakes in STKS are about 25x and 1.5x times their stakes in TACT, with Hilario being the CEO and President of STKS:
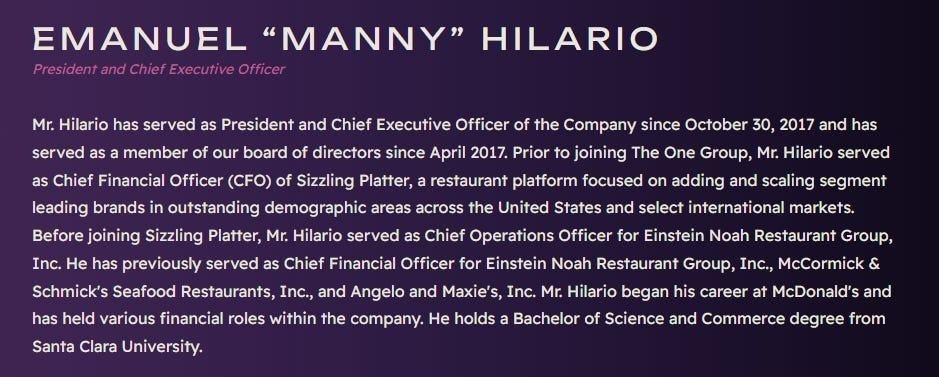
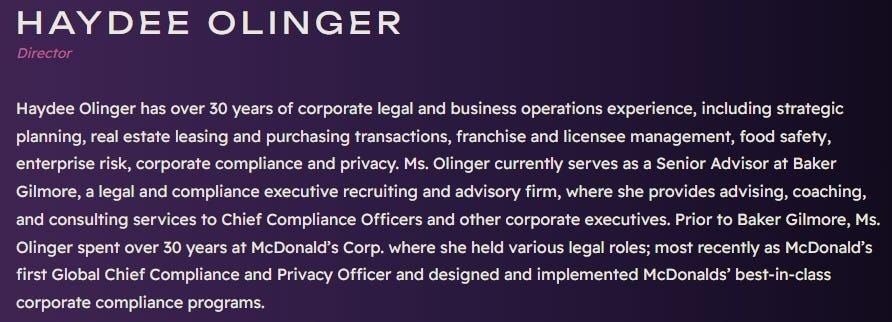
Therefore, we cannot imagine a scenario where Olinger and Hilario are rightly incentivised to act in the best interest of the shareholders of TACT when they both are, together, sitting on two boards serving the fiduciary duty of two different shareholder bases and their economic interest to STKS is many multiples times that of their stakes in TACT, all the while Hilario serves as the CEO of STKS. A Board interlock where more than one board member(one of whom chairs the board of TACT) together serves on another company’s board while the latter company is a customer of the former is a red flag we want resolved urgently, and it is extremely saddening to see that TACT suffers from it.
Governance concern #2: The related party transaction and audit committee
As it was established in the last section, Hilario is the CEO of STKS as well as a director of TACT. We’d imagine that their interests are more aligned with that of STKS than that of TACT due to the magnitude of the difference of their stakes in each company. Unfortunately, our intuition that we would find some physical manifestation of this conflict of interest via related party transactions was proven true:
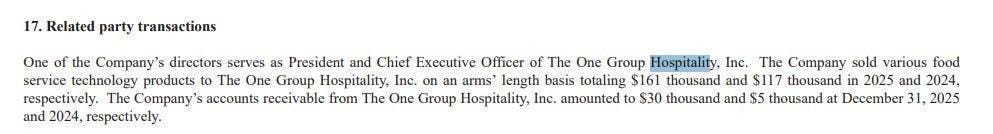
TACT sells products to The One Group Hospitality headed by Hilario. While the dollar amounts may seem immaterial, it is a testament to the long-standing phenomenon that has led to the conclusion that having a two-person board block in two public companies simultaneously can create massive conflicts of interest and it is hard for the board members to serve the fiduciary duties of both(in this case, in our opinion their economic incentives tilt toward STKS rather than TACT):
The directors of a company have a fiduciary duty of loyalty towards its shareholders and if the Chairman of the board holds a higher economic stake in another publicly traded company, as well as another board member being the CEO of that same company, shareholders are entitled to question whether undivided loyalty is realistic within such a structure. Even more egregiously, the audit committee that is supposed to police conflicts of interests and align the incentives of the directors along with the shareholders’ best interests is chaired by Hilario himself, a structure that, in our opinion, cannot credibly police itself:
Shareholders of TACT deserve better directors whose economic interests are aligned with value created in TransAct holdings and we demand a board sweep. More in the section below
The fix: The addition of at least one or two directors with deep expertise on both casino and FST markets to facilitate the sales. Our personal boardroom election pick is Mr. Bart Shuldman
We want people with real economic stake in the business who aren’t entrenched on the boardroom of another public company but also know the business in and out enough to know exactly who the right buyers for the FST/BOHA! business are on the boardroom, as well as someone who, in our view, would prioritise divesting BOHA! given what we believe are its capped growth opportunities (outpaced, in our view, by competitors such as CrunchTime) and its cash consumption. Therefore, we recommend the addition of a few, shareholder-friendly strategists who know the two business segments inside-out to facilitate the sales.
Mr. Shuldman was the CEO of TACT for 27 years from 1996 to 2023 and we don’t believe there is anyone alive that knows the business better than himself at the current moment. Mr. Shuldman was the person who brought the BOHA!/FST unit into TACT’s casino business, and things were going amazing…until Covid-19 hit.
After headcount cuts and a liquidity crunch, TACT lost the ability to invest earnings into BOHA! and in that time, we believe it was surpassed in market penetration by competitors such as CrunchTime, and faces an uphill path to reclaim it. Below is an excerpt from Mr. Shuldman’s public shareholder letter commenting on the FST segment falling behind:
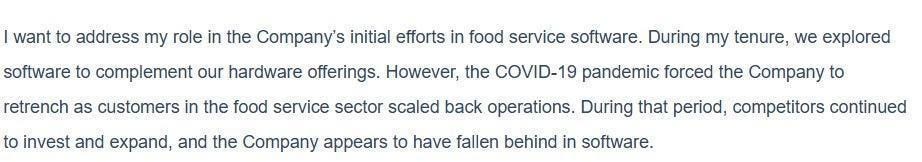
However, that is BOHA!’s software part. BOHA!’s physical terminals are still industry-standard and his public letter describes the BOHA! terminal as among the leading hardware platforms in food service, an asset we believe can command real value from the right strategic buyer. We believe Mr. Shuldman would be well placed to oversee a high-priority sale of BOHA! to the proper strategic buyer, rather than letting the company become the bag-holder of what we believe is a lossmaking asset once Casino is sold first. For clarity: Mr. Shuldman has not endorsed this publication and has no connection to its authors, and his public letter does not call for a sale of BOHA! That request is ours alone.
Moreover, his communications to TACT shareholders in his open letter citing how in 2023 the company retained 3 investment banks to evaluate strategic alternatives showed that the separation of the business into two entities would unlock a substantial amount of value. Bizarrely, this was never realised and we think that Mr. Shuldman is as shocked as we are:
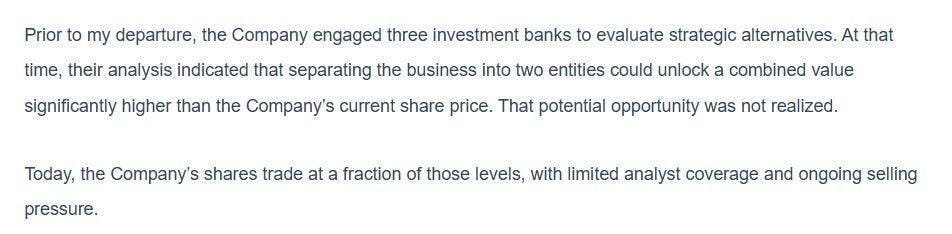
Therefore, given that his deep industry knowledge of being in the field for almost 30 years gives him the increased ability to conduct a sale of the BOHA! unit as well as his pessimism of the BOHA!/FST segment becoming the core business(reading between the lines in his shareholder letters), we think that there is no better candidate to be elected onto the board than Mr. Bart Shuldman.
The fix #2: Consider the choosing of Mr. Dan Friedberg as the Chairman of the board
Out of all the directors on the board, Mr. Friedberg is the only one who owns a substantial stake in the company. He runs 325 capital, a hedge fund which is the vehicle through which he owns a 10% stake in the company. We are shocked that someone who is part of a two-person bloc interlock with a customer of TACT’s with just 0.3% ownership of the company is chairing the board, while Mr. Friedberg who is obviously more incentivised to create shareholder value isn’t.
We believe that, because of his large stake, his incentives align with those of shareholders and he will push for a sale of the BOHA! segment immediately if he were chairing the board, as that is the only logical course of action that benefits both him, 325 Capital and the shareholders. Given that 325 Capital labels itself as a ‘constructive’ partner to boards focused on driving shareholder value in companies, we think that if Mr. Friedberg was handed control on the board’s major decisions, he would do everything in his power with 325 Capital to realise the sheer value trapped inside TACT’s equity. Disclosure: Mr. Friedberg has not endorsed the publication of this piece and has no connection to the authors.
After researching TransAct Technologies in full, we have the following asks to the Board to drive shareholder value:
1. Hire another investment banker to conduct a strategic review of BOHA!/FST segment to hedge out any possible conglomerate discount and to get the best possible prices aimed at strategic buyers
Chuck Gillman’s recent public Schedule 13D filings press for an urgent review of the BOHA! Business:

We demand from the board that this review result in an immediate sale of the BOHA!/FST segment rather than, say, a capital raise for re-investments in the segment. Right now, while the board has put up the Casino segment for sale via a strategic review with BofA, the success of this deal means that shareholders are left with what we believe is a lossmaking segment carrying millions of dollars of corporate overhead. This is value destructive for the shareholders, as the cash received by this deal would evaporate in no time because of the cash-burn of BOHA!/FST in addition to the corporate overhead. The best thing that aligns with the interests for all shareholders is to do a parallel strategic review of the BOHA!/FST segment as well.
As stated before, BOHA!/FST, while lossmaking in our view, is still rich with the potential to be a valuable asset to someone because of its approximately 21,800 active terminals. However, it is crucial that the board doesn’t take our suggestion the wrong way and put the whole company up for sale as one unit: if the board doesn’t hire another investment banker to implement the sale of BOHA! separately(as in, if they try to sell the company as one piece instead of two), shareholders risk having a conglomerate discount being priced into the highest bid. However, with a new prioritised strategic review process by another banker on BOHA!/FST, before/in-parallel to the sale of the Casino Business, the search for a buyer can yield the business being sold with a higher multiple, especially if the able Mr. Shuldman takes the reins of the task of selling BOHA!
We highly advise an immediate sale of the BOHA!/FST segment before/in parallel to the strategic review sale process of the Casino segment via the hiring of an additional investment banker to preserve its multiple with the search of a true, synergistic, strategic buyer.
2. Consider the appointment of Bart Shuldman to the Board of Directors at TACT as part of a roster of new directors with deep industry knowledge
After screening for candidates with the right business acumen for these industries, deep knowledge of the company and its natural buyers, and properly aligned incentives, we believe Mr. Shuldman is the natural candidate to lead the board of directors at TACT. His stake in TACT as well as his firsthand public disclosure that three investment banks’ analysis showed a separation could unlock substantial value make us think that there isn’t anyone else that carries as much knowledge about the businesses of TACT and acumen to sell the assets to the right strategic buyers and also is aligned with driving shareholder value in the world.
We want Mr. Shuldman, or at the very least new capable directors on the board to help with a dual M&A Process where FST/BOHA! is sold first to extract value out of the company for shareholders because of his deep industry knowledge
3. Consider the appointment of Dan Friedberg as the chairman of the board because of his aligned incentives with shareholder value instead of the incumbent 0.3% owner and board interlock participant Ms Olinger.
Mr. Friedberg, being the largest holder of TACT stock within the board of directors is economically incentivised to do right by shareholders, which in this case is letting go of the BOHA! segment via a sale through the announcement of an immediate strategic review by engaging a separate investment bank. Because of his large 10% holding, we do not see anyone else on the board of directors that is fit to be chairing the board because of the lack of incentives to do right by shareholders
We want Mr. Friedberg to lead the Board of Directors and lead the company through a dual M&A Process where FST/BOHA! is sold first to extract value out of the company for shareholders
4. Fix all the Governance issues and the conflicts of interests that entrench the Board
Whoever is chosen to lead the board of directors, there is still a huge elephant in the room that has to be treated: the board is entrenched via a board Interlock, with two directors being on the board of ONE Group Hospitality creating massive conflicts of interests because ONE group is a customer of TACT. Moreover, it is extremely bizarre that one of those directors is Chairing the audit committee for Related Party Transactions, while serving on the board of the counterparty to that related-party arrangement.
We want such conflicts of interests sorted out so proper corporate and ethical governance can return. We suggest electing capable, shareholder-friendly board members such as Mr. Shuldman to the board and Mr. Friedberg as the chairman instead of the incumbents so the company can be led into a clean, dual auction to sell off its operating segments for the best available price to strategic buyers
Disclosure & Disclaimer
You are reading a long-biased opinion piece. Obviously, we may make money if the price of the covered issuer’s stock rises. Important Disclosures : Positions and Third-Party Relationships. This publication reflects the opinions of Ragnarok Research and is for informational purposes only. It is not investment advice or a recommendation to buy, hold, or sell any security. Ragnarok Research may have, now or in the future, financial relationships with one or more unaffiliated third parties (the “Third Parties”). In connection with any such relationship, Ragnarok Research may be entitled to compensation that is contingent upon, and determined by reference to, the Third Parties’ trading profits in the securities of the covered issuer; accordingly, you should assume that Ragnarok Research has, or may have, a direct or indirect economic interest in the price performance of those securities. As of the date and time of publication of any report, you should assume that the Third Parties hold positions in, or derivatives linked to, the securities of the covered issuer, and that Ragnarok Research (possibly along with or through our members, partners, affiliates, employees, and/or consultants), along with our clients and/or investors, may also directly or indirectly hold positions in, or derivatives linked to, those securities, and stands to gain monetarily in such securities unless otherwise stated in the applicable report. You should further assume that, upon or promptly after publication, the Third Parties and/or Ragnarok Research may sell, reduce or close all or a substantial portion — possibly the entirety — of any long positions in the covered issuer. This does not reflect a lack of conviction in the views expressed, but is a matter of portfolio and risk management. Neither Ragnarok Research nor the Third Parties undertakes any obligation to inform any reader of any change in position or view, or to update this report or any information contained herein.
This report expresses our opinions and is provided for informational purposes only. It is not investment, legal, tax or accounting advice, is not a recommendation or solicitation to buy or sell any security, and does not create any advisory or fiduciary relationship between the authors and any reader. Readers should conduct their own research and due diligence, consult their own financial, legal and tax advisers, and draw their own conclusions before making any investment decision. Use of this report is at the reader’s own risk, and to the maximum extent permitted by applicable law the authors shall not be liable for any losses arising from any use of, or reliance upon, this report.
All statements of fact in this report have been obtained from public sources we believe to be accurate and reliable, including filings with the U.S. Securities and Exchange Commission, Company press releases and earnings calls, third-party regulatory filings, and press reports. Such information is presented “as is,” without warranty of any kind, whether express or implied, and we make no representation, express or implied, as to the accuracy, timeliness or completeness of any such information. Readers are encouraged to verify all facts against the primary filings, which are publicly available on the SEC’s EDGAR system. All statements other than statements of fact, including all valuations, estimates, price targets, characterizations of governance arrangements, and views regarding actions the Company or its board should take, are statements of the authors’ opinion, made in good faith on the basis of the publicly disclosed facts cited, and should not be treated as statements of fact. This report contains forward-looking statements that are inherently subject to uncertainty; actual outcomes and events may differ materially from the expectations expressed herein.
Nothing in this report is intended to allege, and nothing herein should be construed as alleging, unlawful conduct, fraud, or breach of fiduciary duty by any person. The criticisms expressed herein concern governance structure, incentive alignment, disclosure practices and capital allocation, matters of opinion on which reasonable people may disagree.
This report has been prepared solely on the basis of publicly available information; the authors do not possess and have not used any material non-public information concerning the Company. Other than any Third-Party relationship of the kind described above, the authors have received no compensation from any person mentioned in this report.
This report is not, and shall not be construed as, a solicitation of a proxy, consent or authorization with respect to any securities of the Company within the meaning of Section 14(a) of the Securities Exchange Act of 1934 and the rules promulgated thereunder, and no proxies are being solicited hereby. This report is likewise not an offer to sell, or a solicitation of an offer to buy, any security in any jurisdiction.