Today, we will be mainly talking about two tickers: Both are Asian Video Game makers which I expect have clear catalysts ahead for outperformance, with a little bit of governance risk which I believe can be hedged away pretty easily.
To all new subscribers,
We are Ragnarok Research, a group of 17 year old investment analysts from Copenhagen, Denmark, doing due diligence into stocks and trying to provide actionable trade ideas. This post about 2 Asian Tickers is a huge event for us: As it’s an opportunity to learn a lot by assimilation as it’s our first post about Asian equities! Let’s dig in.
Why this opportunity exists with GRVY(main holding):
The two companies we are presenting to you today are Gravity Co. Limited(GRVY), and Gungho Entertaintment(TYO: 3765):
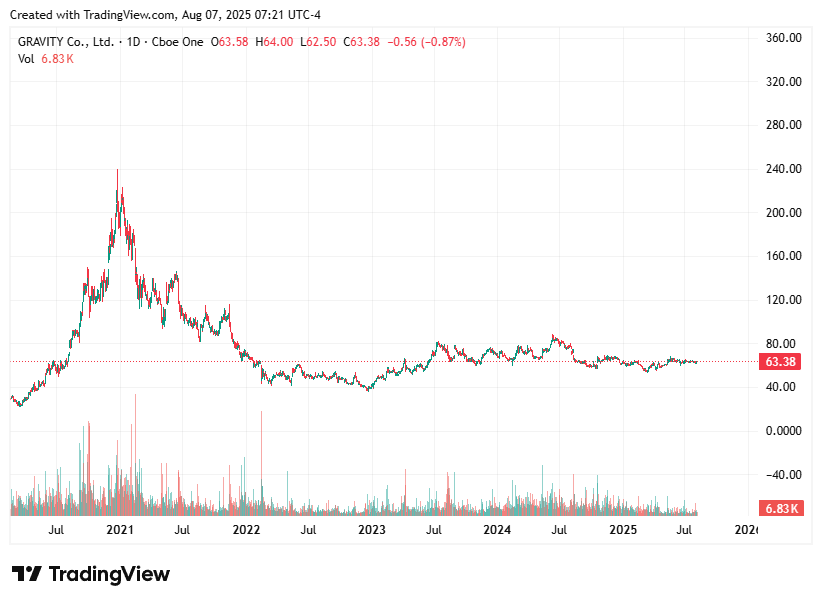
Now as you can see above, the share price of GRVY has severely underperformed. It had a rally in 2021, followed by a breakdown and now it’s in a slump. Why is this the case ? It’s a Korean Video Game maker trading at about 7X pe with 390 million dollars of cash, flexing a market cap of 440 million dollars with zero debt.
So, what’s going on ? The reasons are quite simple:
There has been no meaningful growth in revenues lately. Sure it’s not exactly in a steep decline, but the market doesn’t see any avenues for jumps in revenues or net income
GRVY’s majority owners, Gungho Entertainment are in all intents and purposes, bad operators. They refuse to let GRVY return any cash to shareholders! For instance, look at the share count of GRVY:
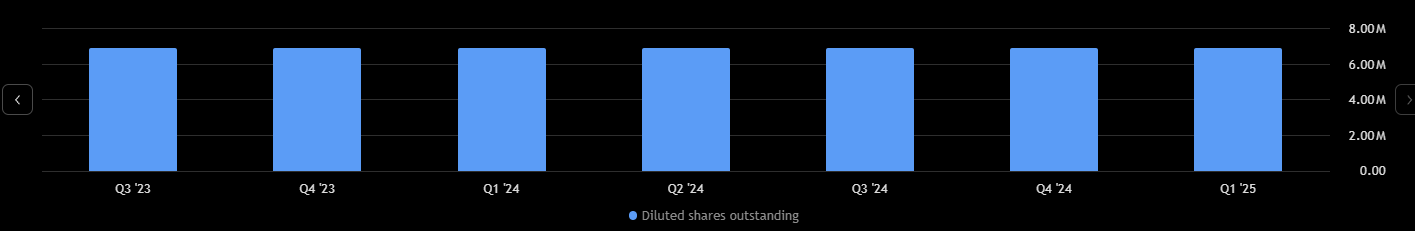
Constant throughout
It’s funny, because GRVY is not exactly a bad business or anything. It’s just, the owners, Gungho, aren’t doing right by shareholders and this has taken a toll on the stock price.
Why this opportunity exists with Gungho(governance hedge):
It is a little easier to see why Gungho’s shares are trading low:
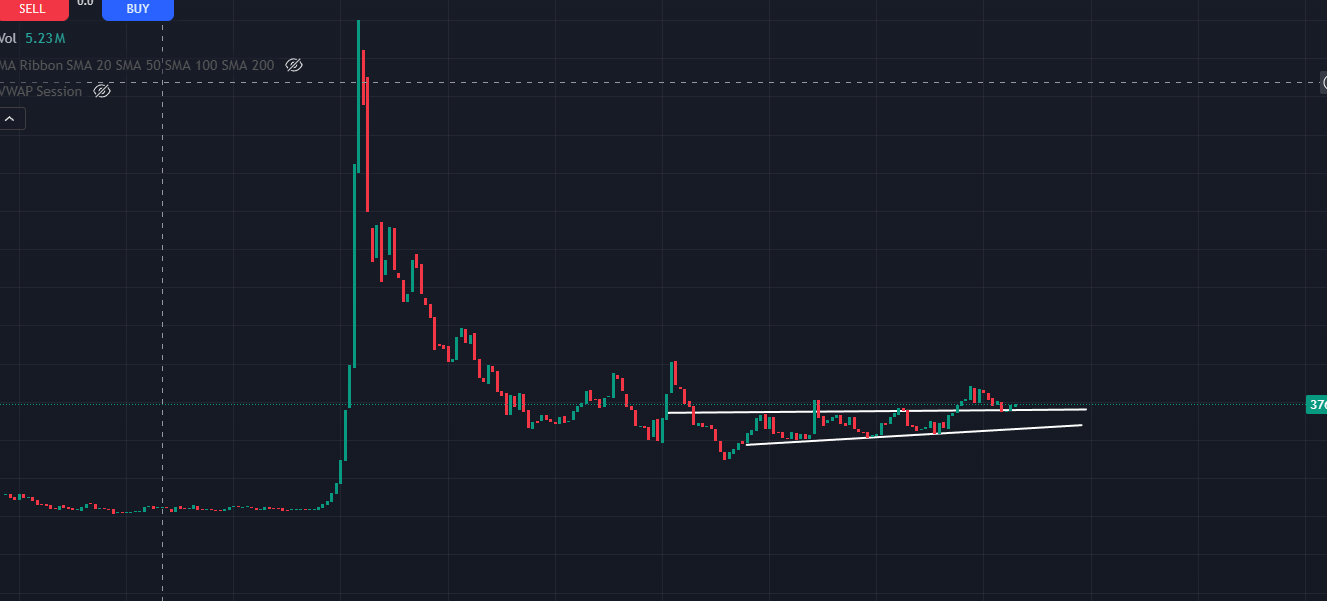
It’s currently trading at a market cap of 160B Yen, with 104B Yen in cash accompanied with 0.7B Yen in Debt, and is now trading at a valuation of 20x PE. Not terrible isn’t it ?
The problem with Gungho is it’s quite literally a one hit wonder. It’s main game, called Puzzles and Dragons, was released a whopping 13 years ago, and Gungho’s present revenues seem to be just milking this one game. I mean, why would they do anything else ? They have enough cash to survive for atleast a decade without doing anything, so why would they waste time coming up with an actual good game ?
There lies the problem. Gungho’s inaction comes in expense of the shareholders with years and years of chronic underperformance.
It’s time for change, and shareholders are infuriated
My core thesis: One of the best Japanese players Strategic Value capital has stepped in to revitalise Gungho. Investors are underappreciating that one of the avenues to do this, might be the revitalisation of GRVY.
GRVY is vastly different from Gungho. Gravity has monetised its ‘Ragnarok’ Game series (haha coincidence??!!) in a very effective manner, and has produced a lot of variations of the Ragnarok game for both mobile and PC over the years. GRVY recently released the game Ragnarok Crush, and a few other games and it seems to be a bang!
A few online mobile ad data have estimated that GRVY’s recent games have started to add huge amounts of topline growth due to popularity in Asia:
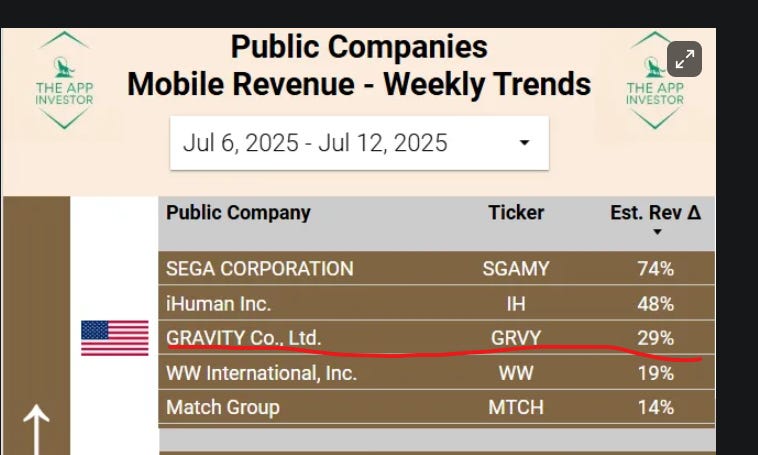
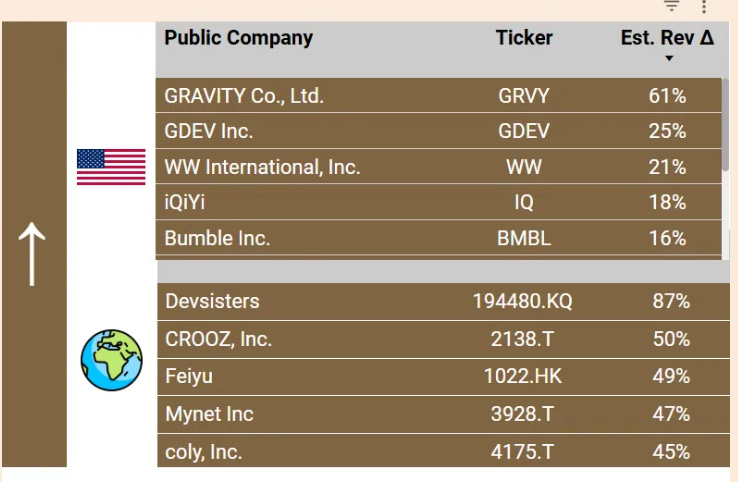
The surprising part is that the GRVY’s NASDAQ listed shares haven’t properly reacted, partly to what I think is a lack of news flow. Moreover, growth in some of the games GRVY has released has led it to be highly ranked in some of GRVY’s main revenue generating demographics:
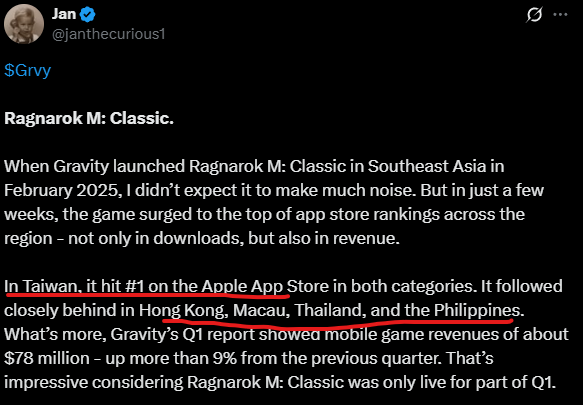
Amazing, isn’t it!
Okay, Ragnarok. We hear you regarding GRVY. But what about Gungho ? What’s the point of going long Gungho?
Glad you asked!
Now, strategic capital are some hardcore activists. After they built a stake in Daidoh, they helped triple the shares since 2022! Most US investors in GRVY, in our opinion, don’t put enough effort into due diligence to actually go to Gungho’s news flow and navigate all the Japanese sites. However, that’s what we’re willing to do!
In a newspaper ad Stratgic posted, here is what they had to say about Gungho:
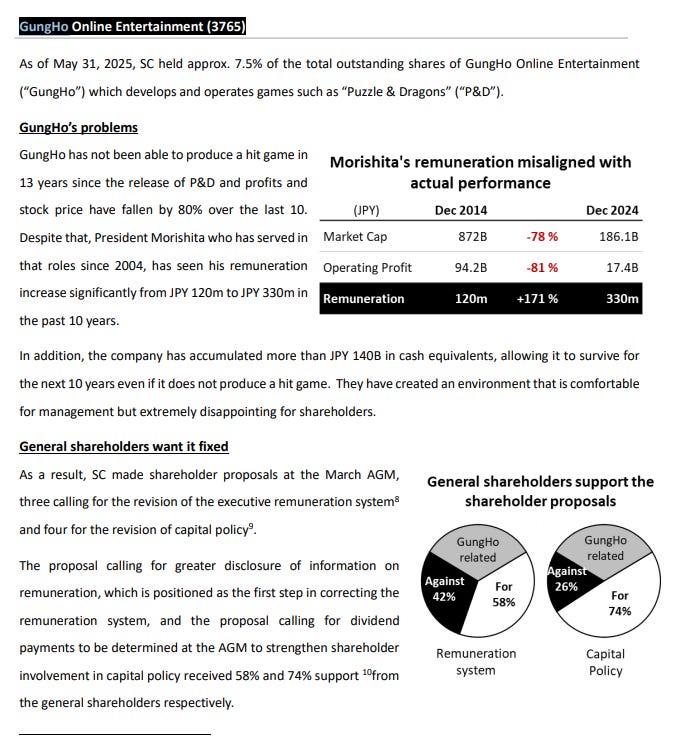
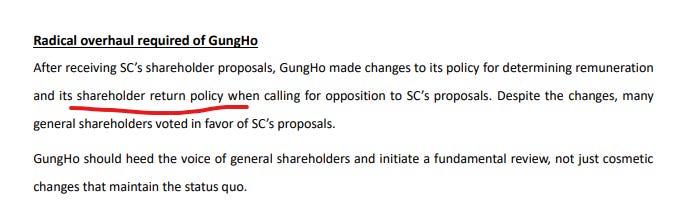
Reading between the lines, here is what I gather form Strategic capital: Their claim about sharheolder return policy signals to me either buybacks or dividends. Increasing CEO renumeration signals to me that they want to out the CEO and are interested in crafting a compensation scheme that incentivises operational efficiency and more emphasis towards game developing and less milking the same game over and over again.
Strategic is outraged that there they have so much cash that they could survive for a while without doing anything. Therefore, they want to put the cash to good use in my opinion: shareholder returns!
Take a look at this document:
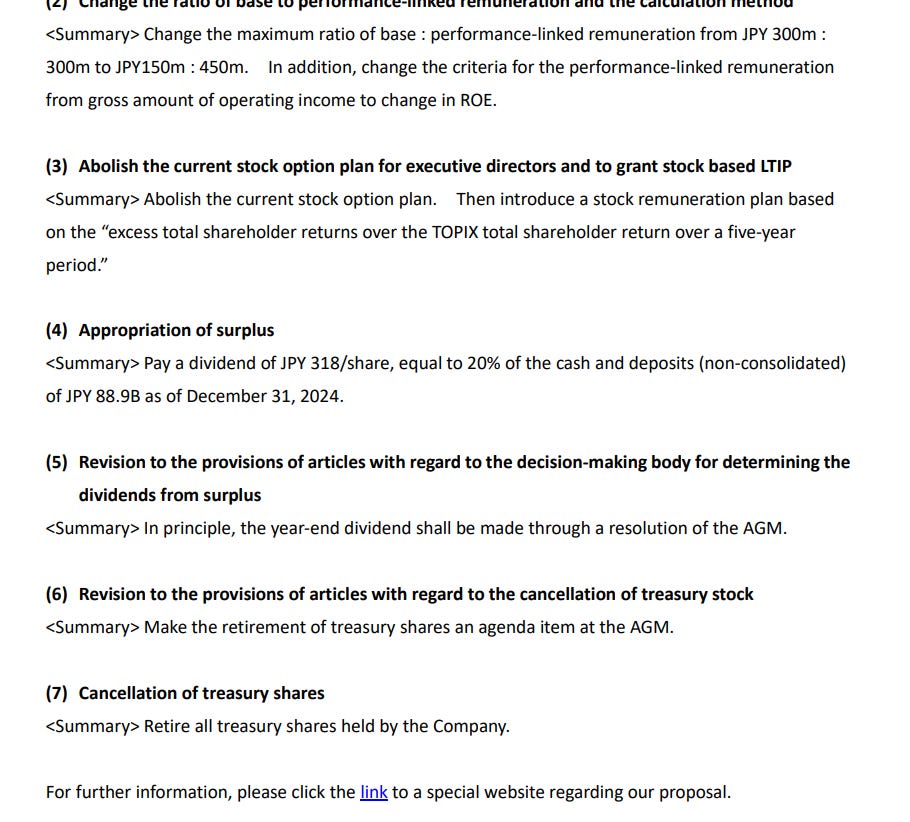
They want to increase the dividend so Gungho shareholders are better rewarded, and change incentive programs so that management is actually monetarily forced to do their jobs.
Now, notice how I called GRVY my ‘main holding’ and Gungho my ‘Governance Hedge’ ? There’s a reason for it.
Let’s take a look at a few scenarios that may unfold:
Strategic Value cap loses(Highly unlikely since shareholders actually support their proposals ):
In this scenario, our majority long holding in GRVY would pay off just a little bit because GRVY’s income statement growth has got me feeling really confident due to their hit game lunch recently
Strategic value cap wins(Highly likely):
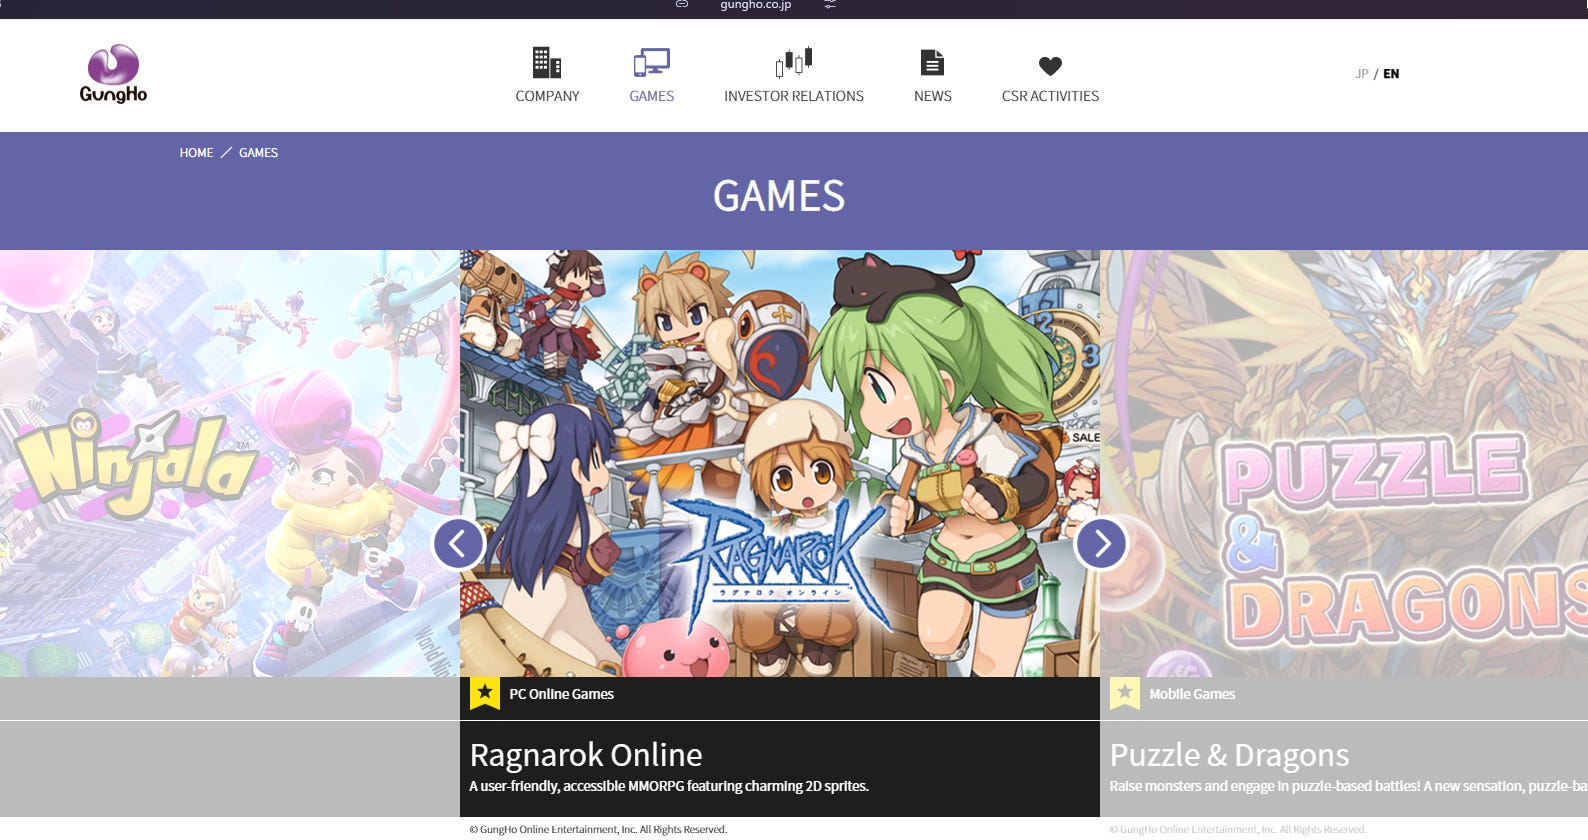
Okay let’s go through this scenario. There’s a reason Gungho’s website has Gravity’s ragnarok series in the front page:
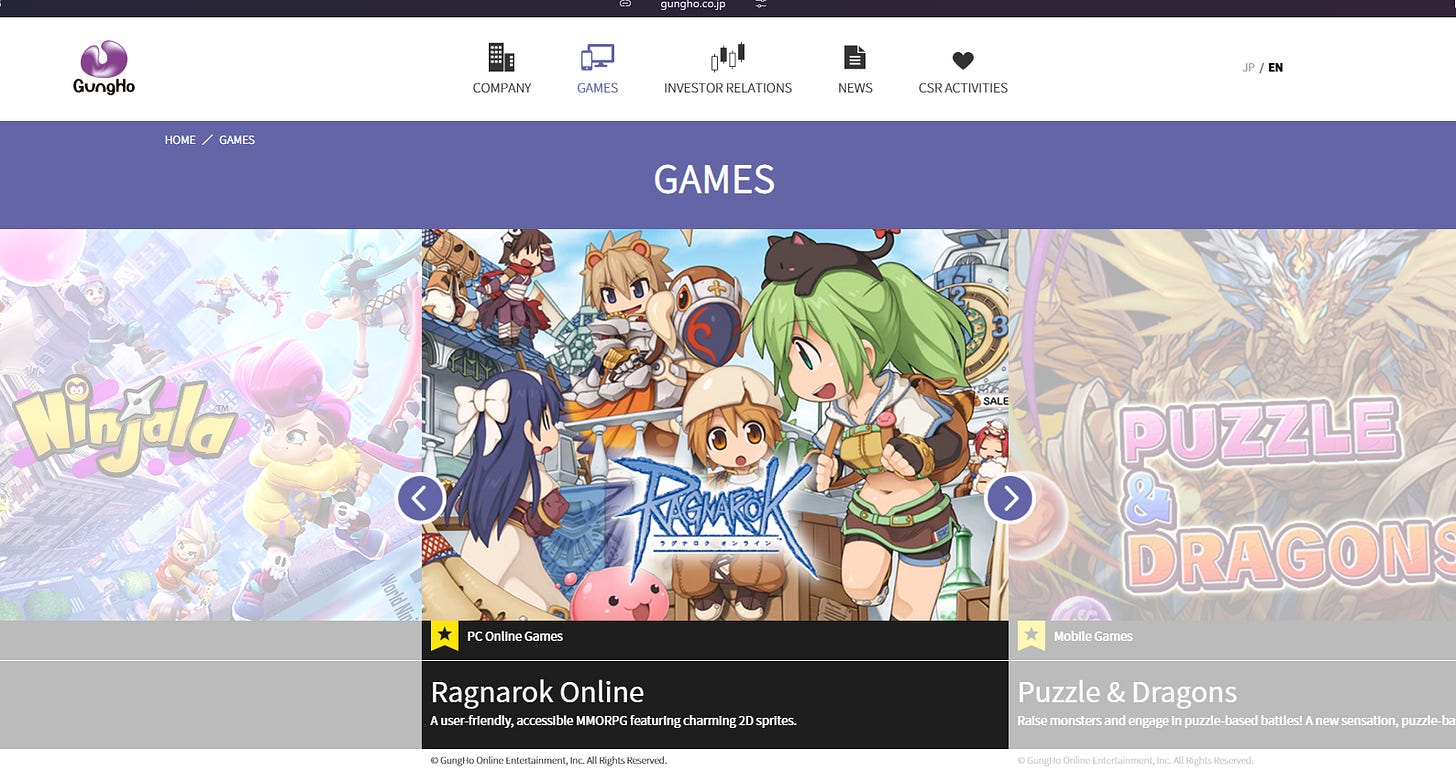
GRVY is much more important to Gungho than shareholders might think. GRVY made about 360 million dollars in 2024, while Gungho made about 700 million dollars in the same period. All in all, if strategic value does get ahold of control of Gungho, I have no doubt that they will focus on GRVY in one way or the other. I see three scenarios here:
- Scenario #1: Gungho (or rather strategic cap) milks GRVY for its cash reserves via a huge dividend from GRVY to Gungho and uses this cash for Gungho’s operations or to return this cash for Gungho’s shareholders(unlikely, and a little bit of a sinister view)I strongly do not believe this would happen, but if it does, I think this would benefit our minority Gungho long position because under Strategic Cap, who are veterans of capital allocation, I’d think this cash is put to good use where it’s either returned to shareholders, or it’s sparsely used for operations and game development
- Scenario #2: There has been a trend in Japanese companies unwinding cross shareholding and using this cash to return value to shareholders(Sort of likely):If Gungho sells its GRVY shares, it’d no longer be the majority owner, and there would be atleast a little scope for better capital allocation. Refer to cluseau's article here. Japan is actually incentivising companies to unwind these cross shareholdings and do something with the excess cash, and Strategic value might actually see the appeal in this! This would mean new, better owners, or better yet, hungrier shareholders craving for better capital allocation! This would mean both our longs would probably make money!
- Scenario #3: Strategic Value Capital makes Gungho pass a resolution to instruct GRVY to buy back their shares(Sorta likely as well)
This might be the cleanest thing that can happen to GRVY shareholders. If Gungho, or Strategic notice that a big part of Gungho’s balance sheet is obviously at a depressed valuation and this can be changed (and remember Strategic is alll for capital return to shareholders), I don’t see why Gungho would look over the possibility of making GRVY do some buybacks!A reflection of how going long Gungho and GRVY hedges out some of the governance risks associated
Folks, to be clear, my main long is GRVY. Out of the three scenarios highlighted above, I see only one scenario where it’s absolutely sure that GRVY will have some short term headwinds, due to it’s cash being dividend-ed out to Gungho. However, this cash that Gungho would have after that operation would somehow be used for the better, assuming Gungho is under the control of Strategic Capital. So, the ‘Governance’ risk of Strategic cap absolutely miking GRVY’s cash reserves and leaving it out for dead(highly highly unlikely that this will happen) is atleast partly hedged out somehow.